-
12 November 2026 07:02:15
- Source: Sharecast

12 November 2026
Atalaya Mining Copper, S.A.
(“Atalaya” or the “Company”)
Q3 and YTD 2026 Financial Results
Record quarterly and nine-month EBITDA and on track to achieve FY2026 guidance
Atalaya Mining (LSE: ATYM) is pleased to announce its unaudited third quarter and nine-month financial results for the period ended 30 September 2026 ("Q3 2026" and “YTD 2026” respectively) together with its interim financial statements.
Highlights
- Copper production of 14.0 kt in Q3 2026 and 37.4 kt in YTD 2026
- Cash Costs of US$2.89/lb in Q3 2026 and US$2.60/lb in YTD 2026
- AISC of US$3.34/lb in Q3 2026 and US$3.11/lb in YTD 2026, which is trending well despite the impact of geopolitical conflicts on the prices of key consumables
- EBITDA of €90.1 million in Q3 2026 and €216.3 million in YTD 2026, which represent new quarterly and nine-month records for Atalaya
- Balance sheet continues to strengthen and will support Atalaya’s various growth initiatives in Spain
- Atalaya remains on track to achieve its FY2026 production and cost guidance
- On 11 November 2026, announced the acquisition of Tharsis Mining for €125 million, providing 100% ownership of two large-scale projects in the Iberian Pyrite Belt
Q3 and YTD 2026 Financial Results Summary
|
Period ended 30 September |
Unit |
Q3 2026 |
Q3 2025 |
YTD 2026 |
YTD 2025 |
|
Revenues from operations |
€k |
187,766 |
106,753 |
452,457 |
361,503 |
|
Operating costs |
€k |
(97,627) |
(76,036) |
(236,130) |
(223,194) |
|
EBITDA |
€k |
90,139 |
30,717 |
216,327 |
138,309 |
|
Profit for the period |
€k |
62,868 |
10,848 |
146,876 |
70,912 |
|
Basic earnings per share |
€ cents/share |
40.9 |
7.8 |
96.4 |
50.5 |
|
Cash flows from operating activities |
€k |
56,995 |
41,729 |
165,555 |
120,006 |
|
Cash flows used in investing activities |
€k |
(19,784) |
(17,992) |
(69,740) |
(59,765) |
|
Cash flows from financing activities |
€k |
(38,713) |
(12,863) |
93,378 |
2,026 |
|
Net cash position (1) |
€k |
342,139 |
89,748 |
342,139 |
89,748 |
|
Working capital surplus |
€k |
333,116 |
93,125 |
333,116 |
93,125 |
|
Average realised copper price (excluding QPs) |
US$/lb |
6.44 |
4.41 |
6.19 |
4.31 |
|
Cu concentrate produced |
tonnes |
81,822 |
74,448 |
223,287 |
231,706 |
|
Cu production |
tonnes |
13,967 |
12,123 |
37,399 |
39,589 |
|
Cash Costs |
US$/lb payable |
2.89 |
2.55 |
2.60 |
2.33 |
|
All-In Sustaining Cost (“AISC”) |
US$/lb payable |
3.34 |
2.98 |
3.11 |
2.84 |
- Net cash = cash and cash equivalents less borrowings, but excludes lease liabilities.
Alberto Lavandeira, CEO, commented:
“We are pleased to have delivered another excellent quarter of financial performance, achieving new records for quarterly and nine-month EBITDA. Supported by strong copper prices and solid production at Proyecto Riotinto, these results have further strengthened our balance sheet, with net cash increasing to €342 million at the end of September.
Despite cost pressures from higher prices for certain key consumables, we remain on track to achieve our FY2026 guidance. We continue to expect copper production at the low end of the guidance range, while maintaining our Cash Cost and AISC guidance.
Our strong financial position provides a solid foundation to support our growth projects in Spain. At Proyecto Masa Valverde, we are preparing to commence access ramp development, while at Proyecto Touro, we continue to progress planning works as we await the environmental impact statement, which we understand is nearing completion. The recent designation of Touro as a Strategic Project by the European Commission further reinforces its importance to Europe's future copper supply.
We are also pleased to have recently announced the acquisition of Tharsis Mining, which expands Atalaya’s presence in the Iberian Pyrite Belt by providing 100% ownership of two substantial past-producing assets with significant resources and exploration potential.
Looking ahead, we remain focused on delivering strong operational performance, maintaining cost discipline and advancing our portfolio of growth projects to create long-term value for our shareholders.”
Results Presentations
Analyst and Investor Presentation
Alberto Lavandeira (CEO) and César Sánchez (CFO) will host a webcast for analysts and investors today at 9:00 GMT.
To access the SparkLive webcast, please visit:
Atalaya Mining Q3 and YTD 2026 Financial Results | SparkLive | LSEG
Investor Meet Company Presentation
In addition, the Company will provide a live presentation via the Investor Meet Company platform today at 11:00 GMT.
To access the Investor Meet Company presentation, please visit:
https://www.investormeetcompany.com/atalaya-mining-copper-sa/register-investor
Q3 and YTD 2026 Operating Results Summary
|
|
Unit |
Q3 2026 |
Q3 2025 |
YTD 2026 |
YTD 2025 |
|
Ore mined |
tonnes |
4,241,682 |
3,726,262 |
11,644,041 |
10,949,563 |
|
Waste mined (1) |
tonnes |
10,994,393 |
9,803,768 |
31,488,455 |
33,763,057 |
|
Ore processed |
tonnes |
4,119,542 |
4,271,614 |
12,292,544 |
12,490,078 |
|
Copper grade |
% |
0.40 |
0.38 |
0.37 |
0.41 |
|
Copper concentrate grade |
% |
17.07 |
16.28 |
16.75 |
17.09 |
|
Copper recovery |
% |
84.26 |
74.45 |
83.40 |
77.48 |
|
Copper concentrate produced |
tonnes |
81,822 |
74,448 |
223,287 |
231,706 |
|
Copper production |
tonnes |
13,967 |
12,123 |
37,399 |
39,589 |
|
Payable copper production |
tonnes |
13,149 |
11,378 |
35,166 |
37,272 |
|
Cash Costs |
US$/lb payable |
2.89 |
2.55 |
2.60 |
2.33 |
|
All-in Sustaining Costs |
US$/lb payable |
3.34 |
2.98 |
3.11 |
2.84 |
- Represents the Cerro Colorado pit only.
Mining
Ore mined was 4.2 million tonnes in Q3 2026 (Q3 2025: 3.7 million tonnes) and 11.6 million tonnes in YTD 2026 (YTD 2025: 10.9 million tonnes).
Waste mined was 11.0 million tonnes in Q3 2026 (Q3 2025: 9.8 million tonnes) and 31.5 million tonnes in YTD 2026 (YTD 2025: 33.8 million tonnes). In addition, waste stripping activities continued at the San Dionisio area.
Processing
Ore processed was 4.1 million tonnes in Q3 2026 (Q3 2025: 4.3 million tonnes) and 12.3 million tonnes in YTD 2026 (YTD 2025: 12.5 million tonnes).
Copper grade was 0.40% in Q3 2026 (Q3 2025: 0.38%) and 0.37% in YTD 2026 (YTD 2025: 0.41%).
Copper recovery was 84.26% in Q3 2026 (Q3 2025: 74.45%) and 83.40% in YTD 2026 (YTD 2025: 77.48%).
Production
Copper production was 13,967 tonnes in Q3 2026 (Q3 2025: 12,123 tonnes) and 37,399 tonnes in YTD 2026 (YTD 2025: 39,589 tonnes). In addition, silver contained in copper concentrate was 0.18 million ounces in Q3 2026 (Q3 2025: 0.31 million ounces) and 0.62 million ounces in YTD 2026 (YTD 2025: 0.93 million ounces).
On-site copper concentrate inventories were 3,259 tonnes at 30 September 2026 (30 June 2026: 11,362 tonnes).
Copper contained in concentrates sold was 15,243 tonnes in Q3 2026 (Q3 2025: 12,234 tonnes) and 37,491 tonnes in YTD 2026 (YTD 2025: 41,664 tonnes).
Cash Cost and AISC Breakdown
|
US$/lb Cu payable |
Q3 2026 |
Q3 2025 |
YTD 2026 |
YTD 2025 |
|
Mining |
1.24 |
1.07 |
1.25 |
0.92 |
|
Processing |
0.92 |
0.94 |
0.93 |
0.83 |
|
Other site operating costs |
0.64 |
0.74 |
0.73 |
0.64 |
|
Total site operating costs |
2.80 |
2.75 |
2.91 |
2.40 |
|
By-product credits |
(0.27) |
(0.43) |
(0.52) |
(0.35) |
|
Freight, treatment charges and other offsite costs |
0.36 |
0.23 |
0.21 |
0.29 |
|
Total offsite costs |
0.09 |
(0.20) |
(0.31) |
(0.07) |
|
Cash Costs |
2.89 |
2.55 |
2.60 |
2.33 |
|
|
|
|
|
|
|
Cash Costs |
2.89 |
2.55 |
2.60 |
2.33 |
|
Corporate costs |
0.14 |
0.10 |
0.13 |
0.09 |
|
Sustaining capital (excluding tailings expansion) |
0.09 |
0.02 |
0.07 |
0.03 |
|
Capitalised stripping costs (1) |
0.20 |
0.18 |
0.26 |
0.28 |
|
Other costs |
0.02 |
0.14 |
0.05 |
0.10 |
|
AISC |
3.34 |
2.98 |
3.11 |
2.84 |
- Represents the Cerro Colorado pit only.
Note: Some figures may not add up due to rounding.
Cash Costs were US$2.89/lb payable copper in Q3 2026 (Q3 2025: US$2.55/lb) and US$2.60/lb payable copper in YTD 2026 (YTD 2025: US$2.33/lb), which were impacted by higher diesel, explosives and electricity prices. Cash Costs in Q3 2026 were also impacted by lower silver revenue, including an unfavourable settlement adjustment for prior silver sales, and higher other offsite costs, but benefitted from higher copper production.
AISC were US$3.34/lb payable copper in Q3 2026 (Q3 2025: US$2.98/lb) and US$3.11/lb payable copper in YTD 2026 (YTD 2025: US$2.84/lb), which were impacted by the same factors as Cash Costs and higher corporate and sustaining capital costs, but partly offset by lower other costs. AISC excludes investments in the tailings dam (consistent with prior reporting) and waste stripping at the San Dionisio area.
Q3 and YTD 2026 Financial Results Highlights
Income Statement
Revenues were €187.8 million in Q3 2026 (Q3 2025: €106.8 million) and €452.5 million in YTD 2026 (YTD 2025: €361.5 million), mainly as a result of higher realised copper prices.
Operating costs were €97.6 million in Q3 2026 (Q3 2025: €76.0 million) and €236.1 million in YTD 2026 (YTD 2025: €223.2 million), mainly due to higher diesel, explosives and electricity prices triggered by the ongoing geopolitical conflicts. Operating costs in Q3 2026 also reflect the de-stocking of concentrate inventories during the quarter.
EBITDA was €90.1 million in Q3 2026 (Q3 2025: €30.7 million) and €216.3 million in YTD 2026 (YTD 2025: €138.3 million), which represent new quarterly and nine-month records for Atalaya.
Profit after tax was €62.9 million in Q3 2026 (Q3 2025: €10.8 million) or 40.9 cents basic earnings per share (Q3 2025: 7.8 cents) and €146.9 million in YTD 2026 (YTD 2025: €70.9 million) or 96.4 cents basic earnings per share (YTD 2025: 50.5 cents).
Cash Flow Statement
Cash flows from operating activities before changes in working capital were €94.8 million in Q3 2026 (Q3 2025: €36.5 million) and €57.0 million after working capital changes (Q3 2025: €41.7 million). For YTD 2026, cash flows from operating activities before changes in working capital were €223.3 million (YTD 2025: €144.7 million) and €165.6 million after working capital changes (YTD 2025: €120.0 million).
Cash flows used in investing activities were €19.8 million in Q3 2026 (Q3 2025: €18.0 million) and €69.7 million in YTD 2026 (YTD 2025: €59.8 million). Key investments in Q3 2026 included €2.4 million in sustaining capex, €5.1 million in capitalised stripping at Cerro Colorado, €10.2 million related to the San Dionisio area and €1.7 million to expand the tailings dam.
Cash flows from financing activities were negative €38.7 million in Q3 2026 (Q3 2025: negative €12.9 million) and positive €93.4 million in YTD 2026 (YTD 2025: positive €2.0 million), reflecting dividend payments, credit facility repayments and proceeds from the January 2026 equity offering.
Balance Sheet
Consolidated cash and cash equivalents were €354.1 million as of 30 September 2026 (31 December 2025: €166.3 million).
Current and non-current borrowings were €11.9 million, resulting in a net cash position of €342.1 million as of 30 September 2026 (31 December 2025: €122.0 million). This represents a further strengthening of Atalaya's balance sheet in Q3 2026, despite an increase in receivables during the quarter.
Inventories of concentrate valued at cost were €4.1 million at 30 September 2026 (31 December 2025: €3.8 million). The total working capital surplus was €333.1 million at 30 September 2026 (31 December 2025: €93.8 million).
Outlook for 2026
Production
For FY2026, Atalaya continues to expect production to be at the low end of the original guidance ranges of 50,000 – 54,000 tonnes of copper and 0.9 – 1.1 million ounces of silver contained in copper concentrate, respectively.
Operating Costs
Ongoing geopolitical conflicts, including those in the Middle East and Ukraine-Russia, continue to contribute to volatility in energy markets and higher prices for certain key consumables, such as diesel and explosives. In addition, these developments have contributed to electricity price volatility in Spain during periods of peak summer demand.
Despite these pressures, Atalaya continues to expect FY2026 Cash Costs and AISC to remain within the previously announced guidance ranges of US$2.60 – 2.90/lb and US$3.10 – 3.40/lb of payable copper, respectively.
Non-Sustaining Capital Investments
Guidance for FY2026 total non-sustaining capital investments remains at €52 – 80 million.
Exploration and Other Project Expenses
Exploration and other project expenses for FY2026 are now expected to be €7 – 9 million, an increase from prior guidance of €5 – 7 million.
Acquisition of Tharsis Mining, S.L. (Subsequent Event)
On 11 November 2026, Atalaya announced that it had completed the acquisition of 100% of the shares of Tharsis Mining, S.L., a private Spanish company that owns the past-producing Tharsis and La Zarza projects, which are located west of Atalaya’s Riotinto complex in southwest Spain.
The transaction consolidates Atalaya’s footprint in the Iberian Pyrite Belt through the acquisition of two large-scale polymetallic deposits which are expected to become important growth options for the Company and be sequenced beyond the development of Proyecto Touro.
Total consideration for the acquisition is €125 million, consisting of €75 million in upfront cash consideration paid on completion and deferred cash consideration of €50 million payable within 12 months of the closing date. The upfront consideration was satisfied from Atalaya’s existing cash resources.
Asset Portfolio Update
Proyecto Riotinto
Stripping activities at San Dionisio continued, with total waste mined of 3.1 million tonnes in Q3 2026, which was lower than planned due to delays in the relocation of a power line by the electricity supplier. San Dionisio represents a key component of Atalaya's strategy to increase copper production by sourcing higher-grade material from deposits throughout the Riotinto District to be blended with ore from Cerro Colorado.
At the San Antonio polymetallic deposit, which is located immediately east of the Cerro Colorado pit, the current drilling campaign has been completed and the new data will support an update to the resource model.
Atalaya continues to progress engineering studies for modifications to the Riotinto processing plant that would enable the simultaneous treatment of copper and polymetallic ores. In parallel, the Company is evaluating opportunities to produce a pyrite concentrate from its tailings streams for potential sale into the sulphuric acid market.
E-LIX Phase I Plant
During Q3 2026, the E-LIX plant has been processing high-zinc, low-copper bulk concentrates and producing upgraded saleable copper concentrates and zinc precipitates. Operational costs are currently under review, with the core objectives for the remainder of FY2026 being to demonstrate breakeven and consistent plant performance.
Riotinto District – Proyecto Masa Valverde ("PMV")
Surface preparation works continue at Proyecto Masa Valverde, while the start of access ramp development is expected to begin in the coming weeks. The project has received the key environmental and exploitation permits required for development.
Exploration activities continue to focus on the copper-rich stockwork-style zones, which are expected to be amenable for processing at the existing Riotinto facilities. Recent results have been favourable and confirm the continuity and expansion of the high-grade mineralisation.
Photo 1: PMV Surface Works
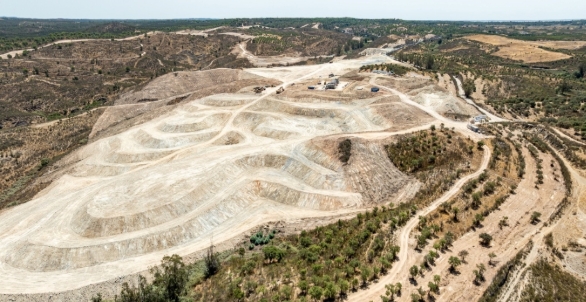
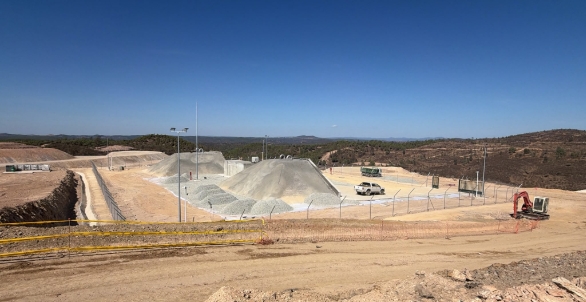
Photo 2: PMV Explosives Storage Magazines
Proyecto Touro
On 9 October 2026, the European Commission announced that it had designated Proyecto Touro as a Strategic Project under the European Union’s Critical Raw Materials Act (“CRMA”). This designation recognises the strategic importance of Proyecto Touro in contributing to a secure and sustainable European supply of copper, which has been included on the EU’s list of strategic raw materials as a result of being essential to electrification, energy infrastructure and industrial development.
Atalaya and its local entity Cobre San Rafael ("CSR") believe that the approval process for the Touro environmental impact statement ("DIA") is nearing completion. Meanwhile, CSR continues to advance early works including detailed engineering and procurement activities.
Proyecto Ossa Morena
At the Guijarro gold project, the 2026 drilling programme concluded after completing 16 holes.
Skellefte Belt and Rockliden (Sweden)
In November 2024, Atalaya announced that it had entered into two binding agreements with Mineral Prospektering i Sverige AB ("MPS") pursuant to which Atalaya can earn an initial 75% interest in two separate land packages in Sweden. The Skellefte Belt land package ("Skellefte Belt Project") and the Rockliden land package ("Rockliden Project") are located in two notable districts that host many large-scale volcanogenic massive sulphide ("VMS") deposits and mines owned by Boliden AB. Both regions are underexplored and could increase Atalaya's exposure to critical minerals in Europe.
At the end of Q2 2026, Atalaya fulfilled its Stage 1 funding commitments for the Skellefte Belt Project, thereby earning a 51% interest in the project. During Q3 2026, Fixed-Loop Electromagnetic (FLEM) and Borehole Electromagnetic (BHEM) geophysical surveys were conducted and their results interpreted during the quarter, identifying promising new drill targets and potential extensions of known mineralisation. Drilling resumed on 22 September 2026 within the Kedtrask nr 1 licence, with the first two holes of the campaign intersecting massive sulphides at the anticipated depths, extending the mineralisation identified during the previous winter drilling campaign further down-dip.
At the Rockliden Project, a Fixed-Loop Electromagnetic (FLEM) survey was completed during Q3 2026, with interpretation of the results currently underway.
The person responsible for arranging release of this Announcement on behalf of the Company is César Sánchez (CFO).
This announcement contains information which, prior to its publication constituted inside information for the purposes of Article 7 of Regulation (EU) No 596/2014.
Contacts:
|
SEC Newgate UK |
Clotilde Gros / George Esmond / Gwen Samuel |
+44 20 3757 6882 |
|
Atalaya Mining |
Michael Rechsteiner |
+34 959 59 28 50 |
About Atalaya Mining Copper, S.A.
Atalaya is a European copper producer that owns and operates the Proyecto Riotinto complex in southwest Spain. Atalaya’s shares trade on the London Stock Exchange’s Main Market under the symbol “ATYM” and Atalaya is a FTSE 250 Index constituent.
Atalaya’s operations include the Cerro Colorado open pit mine and a modern 15 Mtpa processing plant, which has the potential to become a central processing hub for ore sourced from its wholly owned regional projects around Riotinto, such as Proyecto Masa Valverde and Proyecto Riotinto East. In addition, Atalaya has a phased earn-in agreement for up to 80% ownership of Cobre San Rafael S.L., which fully owns the Proyecto Touro brownfield copper project in the northwest of Spain, as well as a 99.9% interest in Proyecto Ossa Morena. For further information, please visit www.atalayamining.com
ATALAYA MINING COPPER, S.A.
MANAGEMENT’S REVIEW AND
UNAUDITED CONDENSED CONSOLIDATED INTERIM
FINANCIAL STATEMENTS
30 September 2026
Management review report
Notice to Reader
The accompanying Unaudited Condensed Consolidated Interim Financial Statements of Atalaya Mining Copper, S.A. have been prepared by and are the responsibility of its management.
Introduction
This report provides an overview and analysis of the financial results of operations of Atalaya Mining Copper, S.A. and its subsidiaries (“Atalaya”, the “Company” and/or “Group”), to enable the reader to assess material changes in the financial position between 31 December 2025 and 30 September 2026 and results of operations for the three and nine months ended 30 September 2026 and 2025.
This report has been prepared as of 11 November 2026. The analysis hereby included is intended to supplement and complement the Unaudited Condensed Consolidated Interim Financial Statements and notes thereto (“Financial Statements”) as at and for the period ended 30 September 2026. The reader should review the Financial Statements in conjunction with the review of this report and with the Audited Consolidated Financial Statements for the year ended 31 December 2025, and the Unaudited Condensed Consolidated Interim Financial Statements for the period ended 30 September 2025. These documents can be found on Atalaya’s website at www.atalayamining.com
Atalaya prepares its Annual Financial Statements in accordance with International Financial Reporting Standards as adopted by the European Union (IFRS-EU) and the interpretations of the IFRS Interpretations Committee (IFRS IC) approved by Regulations of the European Commission, and its Unaudited Condensed Consolidated Interim Financial Statements in accordance with International Accounting Standard 34: Interim Financial Reporting. The currency referred to in this document is the Euro, unless otherwise specified.
Forward-looking statements
This report may include certain “forward-looking statements” and “forward-looking information” under applicable securities laws. Except for statements of historical fact, certain information contained herein constitute forward-looking statements. Forward-looking statements are frequently characterised by words such as “plan”, “expect”, “project”, “intend”, “believe”, “anticipate”, “estimate”, and other similar words, or statements that certain events or conditions “may” or “will” occur. Forward-looking statements are based on the opinions and estimates of management at the date the statements are made, and are based on a number of assumptions and subject to a variety of risks and uncertainties and other factors that could cause actual events or results to differ materially from those projected in the forward-looking statements. Assumptions upon which such forward-looking statements are based include that all required third party regulatory and governmental approvals will be obtained. Many of these assumptions are based on factors and events that are not within the control of Atalaya and there is no assurance they will prove to be correct. Factors that could cause actual results to vary materially from results anticipated by such forward-looking statements include changes in market conditions and other risk factors discussed or referred to in this report and other documents filed with the applicable securities regulatory authorities. Although Atalaya has attempted to identify important factors that could cause actual actions, events or results to differ materially from those described in forward-looking statements, there may be other factors that cause actions, events or results not to be anticipated, estimated or intended. There can be no assurance that forward-looking statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Atalaya undertakes no obligation to update forward-looking statements if circumstances or management’s estimates or opinions should change except as required by applicable securities laws. The reader is cautioned not to place undue reliance on forward-looking statements.
- Incorporation and description of the Business
Atalaya Mining Copper, S.A. was incorporated in Cyprus on 17 September 2004 as a private company with limited liability under the Companies Law, Cap. 113 and was converted to a public limited liability company on 26 January 2005. Its registered office after the cross-border conversion finished on 10 January 2025 is Paseo de las Delicias, 1, 3, 41001, Sevilla, Spain.
The Company was first listed on the Alternative Investment Market (AIM) of the London Stock Exchange in May 2005, trading under the symbol ATYM. On 29 April 2024, the Company was admitted to the premium listing segment of the Official List maintained by the FCA and to trading on the main market of the London Stock Exchange. After completion of the cross-border conversion, the Company’s shares commenced trading under “Atalaya Mining Copper, S.A.” on 10 January 2025 and the nominal value of the Company’s shares were also adjusted from 7.5p to €0.09 per share.
Atalaya is a European mining and development company. The strategy is to evaluate and prioritise metal production opportunities in several jurisdictions throughout the well-known belts of base and precious metal mineralisation in Spain, elsewhere in Europe and Latin America.
The Group has interests in four mining projects: Proyecto Riotinto, Proyecto Touro, Proyecto Masa Valverde and Proyecto Ossa Morena. In addition, the Group has an earn-in agreement to acquire two investigation permits at Proyecto Riotinto East.
In November 2024, Atalaya entered into earn-in agreements on two exploration projects in Sweden (the Skellefte Belt and Rockliden) located in prospective volcanogenic massive sulphide ("VMS") districts.
Proyecto Riotinto
The Company owns and operates through a wholly owned subsidiary, “Proyecto Riotinto”, an open-pit copper mine located in the Iberian Pyrite Belt, in the Andalusia region of Spain, approximately 65 km northwest of Seville. A brownfield expansion of this mine was completed in 2019 and successfully commissioned by Q1 2020.
Proyecto Touro
As described in the Annual Report 2025, the Group initially acquired a 10% stake in Cobre San Rafael, S.L. (“CSR”), the owner of Proyecto Touro, under an earn-in agreement that allows the Group to acquire up to 80% of the copper project. Proyecto Touro, located in Galicia (north-west Spain), is currently in the permitting process.
In July 2017, the Group announced that it had executed the option to acquire 10% of CSR, a wholly owned subsidiary of Explotaciones Gallegas S.L. The earn-in agreement was structured in four phases, enabling the Group to gradually increase its stake in CSR up to 80%:
- Phase 1 – The Group paid €0.5 million to secure an exclusive right to fund up to a maximum of €5.0 million to support the permitting and financing stages.
- Phase 2 – Upon receipt of permits, the Group is required to pay €2.0 million to acquire an additional 30% interest in the project (cumulative 40%).
- Phase 3 – Once development capital is secured and construction commences, the Group is required to pay €5.0 million to acquire an additional 30% interest in the project (cumulative 70%).
- Phase 4 – Upon declaration of commercial production, the Group purchases an additional 10% interest (cumulative 80%) in consideration for a 0.75% Net Smelter Return royalty, with a buyback option.
The agreement was structured to ensure that payments would be made progressively as the project is de-risked, permitted, and becomes operational.
On 24 June 2024, Atalaya announced that Proyecto Touro, through CSR, had been declared a Strategic Industrial Project (“Proyecto Industrial Estratégico” or “PIE”) by the Council of the Xunta de Galicia (“XdG”). Under Galician legislation, PIE status sought to simplify administrative procedures and aimed to shorten permitting timelines.
This declaration highlighted the XdG's commitment to promoting new investment in the region and aligned with the objectives of the European Union. As copper was considered a strategic raw material by the EU, the project was recognised for its potential to become a sustainable European source of copper production.
The XdG continued its review under the simplified procedures applicable to PIE projects. The public information period, which informed nearby communities and organisations about the proposed project, concluded on 31 January 2025. At that time, CSR was focused on analysing and responding to feedback from the public and assessing sectoral reports issued by various departments of the XdG.
As a result of developments during 2024, the Group concluded that it was likely that phases 2, 3 and 4 of the Touro project would be completed. Accordingly, in line with the Group's accounting policy on contingent payments, it recognised an intangible asset of €16.5 million as of year-end, together with the related contingent liabilities.
In accordance with the Group's policy on non-controlling interests, 20% of the newly recognised intangible asset was allocated to non-controlling interests, amounting to €3.3 million.
As also disclosed in the Annual Report 2024 and reflecting the Group’s updated expectations regarding the completion of future phases, the Group reversed a previously recorded impairment from 2019 of €6.9 million, which related to capitalised expenses associated with Proyecto Touro.
In parallel, the Company continued to engage with local stakeholders through recruitment initiatives and maintained its water treatment operations to improve water quality in rivers around Touro.
Furthermore, the Company carried out infill and step-out drilling programmes, focused on areas within the initial mine plan where mineralisation remained open.
Proyecto Masa Valverde
On 21 October 2020, the Company announced that it had entered into a definitive purchase agreement to acquire 100% of the shares of Cambridge Mineria España, S.L. (since renamed Atalaya Masa Valverde, S.L.U.), a Spanish company which fully owns the Masa Valverde polymetallic project located in Huelva (Spain). Under the terms of the agreement Atalaya will make an aggregate €1.4 million cash payment in two approximately equal instalments. The first payment is to be executed once the project is permitted and the second and final payment when first production is achieved from the concession.
In November 2023, the exploitation permit for the Masa Valverde and Majadales deposits was officially granted. Following this milestone, in January 2024, the Company made a payment of €0.7 million as part of the process associated with the granted permits.
Proyecto Ossa Morena
In December 2021, Atalaya announced the acquisition of a 51% interest in Rio Narcea Nickel, S.L., which owned 9 investigation permits. The acquisition also provided a 100% interest in three investigation permits that are also located along the Ossa-Morena Metallogenic Belt. In Q3 2022, Atalaya increased its ownership interest in POM to 99.9%, up from 51%, following completion of a capital increase that will fund exploration activities. During 2022 Atalaya rejected 8 investigation permits.
Atalaya will pay a total of €2.5 million in cash in three instalments and grant a 1% net smelter return (“NSR”) royalty over all acquired permits. The first payment of €0.5 million was made following execution of the purchase agreement. The second and third instalments of €1 million each will be made once the environmental impact statement (“EIS”) and the final mining permits for any project within any of the investigation permits acquired under the agreement are secured. In accordance with the agreement, these outstanding instalments are disclosed as a non-current payable to the sellers.
Proyecto Riotinto East
In December 2020, Atalaya entered into a Memorandum of Understanding with a local private Spanish company to acquire a 100% beneficial interest in three investigation permits (known as Peñas Blancas, Cerro Negro and Herreros investigation permits), which cover approximately 12,368 hectares and are located immediately east of Proyecto Riotinto. After a short drilling campaign, the Los Herreros investigation permit was rejected in June 2022. Proyecto Riotinto East consists of the remaining two investigation permits, Peñas Blancas and Cerro Negro, totalling 10,016 hectares.
Skellefte Belt Project and Rockliden Project
During 2024, the Group entered into earn-in agreements with Mineral Prospektering i Sverige AB (“MPS”) in relation to the Skellefte Belt Project and the Rockliden Project, both situated in well-established volcanogenic massive sulphide districts renowned for their mineral resource potential.
Investment in Lara Exploration Ltd
On 2 April 2026, Atalaya announced that it had acquired 4,500,000 shares of Lara Exploration Ltd. (TSX-V: LRA) for C$13.5 million. The shares were acquired via private placement at a price of C$3.00 per share and represent approximately 7.3% of Lara's issued and outstanding shares following completion of the private placements as announced by Lara on 1 April 2026. Atalaya acquired the shares for investment purposes.
- Overview of Operational Results
Proyecto Riotinto
The following table presents a summarised statement of operations of Proyecto Riotinto for the three and nine months ended 30 September 2026 and 2025, respectively.
|
Units expressed in accordance with the international system of units (SI) |
Unit |
Q3 2026 |
Q3 2025 |
YTD 2026 |
YTD 2025 |
|
Ore mined |
tonnes |
4,241,682 |
3,726,262 |
11,644,041 |
10,949,563 |
|
Waste mined (1) |
tonnes |
10,994,393 |
9,803,768 |
31,488,455 |
33,763,057 |
|
Ore processed |
tonnes |
4,119,542 |
4,271,614 |
12,292,544 |
12,490,078 |
|
Copper grade |
% |
0.40 |
0.38 |
0.37 |
0.41 |
|
Copper concentrate grade |
% |
17.07 |
16.28 |
16.75 |
17.09 |
|
Copper recovery rate |
% |
84.26 |
74.45 |
83.40 |
77.48 |
|
Copper concentrate produced |
tonnes |
81,822 |
74,448 |
223,287 |
231,706 |
|
Copper production |
tonnes |
13,967 |
12,123 |
37,399 |
39,589 |
|
Payable copper production |
tonnes |
13,149 |
11,378 |
35,166 |
37,272 |
|
Cash Costs * |
US$/lb payable |
2.89 |
2.55 |
2.60 |
2.33 |
|
All-in Sustaining Cost (“AISC”) * |
US$/lb payable |
3.34 |
2.98 |
3.11 |
2.84 |
- Represents the Cerro Colorado pit only.
(*) Refer Section 5 of this Management Review.
|
US$/lb Cu payable |
Q3 2026 |
Q3 2025 |
YTD 2026 |
YTD 2025 |
|
Mining |
1.24 |
1.07 |
1.25 |
0.92 |
|
Processing |
0.92 |
0.94 |
0.93 |
0.83 |
|
Other site operating costs |
0.64 |
0.74 |
0.73 |
0.64 |
|
Total site operating costs |
2.80 |
2.75 |
2.91 |
2.40 |
|
By-product credits |
(0.27) |
(0.43) |
(0.52) |
(0.35) |
|
Freight, treatment charges and other offsite costs |
0.36 |
0.23 |
0.21 |
0.29 |
|
Total offsite costs |
0.09 |
(0.20) |
(0.31) |
(0.07) |
|
Cash Costs |
2.89 |
2.55 |
2.60 |
2.33 |
|
|
|
|
|
|
|
Cash Costs |
2.89 |
2.55 |
2.60 |
2.33 |
|
Corporate costs |
0.14 |
0.10 |
0.13 |
0.09 |
|
Sustaining capital (excluding tailings expansion) |
0.09 |
0.02 |
0.07 |
0.03 |
|
Capitalised stripping costs (1) |
0.20 |
0.18 |
0.26 |
0.28 |
|
Other costs |
0.02 |
0.14 |
0.05 |
0.10 |
|
AISC |
3.34 |
2.98 |
3.11 |
2.84 |
- Represents the Cerro Colorado pit only.
Note: Some figures may not add up due to rounding.
Three months operational review
Mining
Ore mined was 4.2 million tonnes in Q3 2026 (Q3 2025: 3.7 million tonnes), compared with 4.0 million tonnes in Q2 2026.
Waste mined was 11.0 million tonnes in Q3 2026 (Q3 2025: 9.8 million tonnes), compared with 10.3 million tonnes in Q2 2026. In addition, waste stripping activities continued at the San Dionisio area.
Processing
The plant processed 4.1 million tonnes of ore in Q3 2026 (Q3 2025: 4.3 million tonnes), compared with 4.1 million tonnes in Q2 2026. This reflects ongoing strong plant performance, above the 15 million tonne per annum nameplate capacity.
Copper grade in Q3 2026 was 0.40% (Q3 2025: 0.38%), compared with 0.39% in Q2 2026.
Copper recovery was 84.26% in Q3 2026 (Q3 2025: 74.45%), compared with 83.91% in Q2 2026. The increase reflects the processing of ores with more favourable metallurgical characteristics.
Production
Copper production was 13,967 tonnes in Q3 2026 (Q3 2025: 12,123 tonnes), compared with 13,493 tonnes in Q2 2026. The increase was the result of higher recoveries and higher grades, which more than offset slightly lower throughput compared with Q3 2025.
On-site copper concentrate inventories stood at 3,259 tonnes at 30 September 2026, compared with 11,362 tonnes at 30 June 2026.
Copper contained in concentrates sold was 15,243 tonnes in Q3 2026 (Q3 2025: 12,234 tonnes), compared with 12,493 tonnes in Q2 2026.
Nine months operational review
Copper production during YTD 2026 was 37,399 tonnes, compared with 39,589 tonnes in the same period of 2025. Lower production was primarily the result of lower copper grades and slightly lower ore throughput, partly offset by higher recoveries.
Payable copper in concentrates was 35,166 tonnes, compared with 37,272 tonnes of payable copper in YTD 2025.
Ore mined in YTD 2026 was 11.6 million tonnes, compared with 10.9 million tonnes during YTD 2025. Ore processed was 12.3 million tonnes, compared with 12.5 million tonnes in YTD 2025.
Ore grade during YTD 2026 was 0.37% Cu, compared with 0.41% Cu in YTD 2025. Copper recovery was 83.40%, compared to 77.48% in the same period of the previous year.
Concentrate production amounted to 223,287 tonnes, compared with 231,706 tonnes in YTD 2025.
- Outlook
The forward-looking information contained in this section is subject to the risk factors and assumptions contained in the cautionary statement on forward-looking statements section of this report. Should the Company consider the current guidance no longer achievable, then the Company will provide a further update.
Operational guidance
Proyecto Riotinto operational guidance for 2026 is as follows:
|
|
Unit |
Guidance 2026 |
|
Ore mined |
million tonnes |
15.5 – 16.0 |
|
Waste mined (1) |
million tonnes |
38 – 44 |
|
Ore processed |
million tonnes |
15.8 – 16.2 |
|
Copper grade |
% |
0.36 – 0.39 |
|
Copper recovery |
% |
80 – 83 |
|
Copper production |
tonnes |
50,000 – 54,000 (2) |
|
Cash Costs |
US$/lb payable |
US$2.60 – 2.90 |
|
All-in sustaining cost |
US$/lb payable |
US$3.10 – 3.40 |
- Represents the Cerro Colorado pit only. Waste guidance is 53 – 62 million tonnes when including the San Dionisio pit.
- Low end.
Production
For FY2026, Atalaya continues to expect production to be at the low end of the original guidance ranges of 50,000 – 54,000 tonnes of copper and 0.9 – 1.1 million ounces of silver contained in copper concentrate, respectively.
Operating Costs
Ongoing geopolitical conflicts, including those in the Middle East and Ukraine-Russia, continue to contribute to volatility in energy markets and higher prices for certain key consumables, such as diesel and explosives. In addition, these developments have contributed to electricity price volatility in Spain during periods of peak summer demand.
Despite these pressures, Atalaya continues to expect FY2026 Cash Costs and AISC to remain within the previously announced guidance ranges of US$2.60 – 2.90/lb and US$3.10 – 3.40/lb of payable copper, respectively.
Non-Sustaining Capital Investments
Guidance for FY2026 total non-sustaining capital investments remains at €52 – 80 million.
Exploration and Other Project Expenses
Exploration and other project expenses for FY2026 are now expected to be €7 – 9 million, an increase from prior guidance of €5 – 7 million.
- Overview of the Financial Results
The following table presents summarised consolidated income statements for the three and nine months ended 30 September 2026, with comparatives for the three and nine months ended 30 September 2025, respectively.
|
(Euro 000’s) |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
|
|
|
|
|
|
Revenues |
187,766 |
106,753 |
452,457 |
361,503 |
|
Costs of sales |
(92,933) |
(72,242) |
(223,396) |
(212,474) |
|
Corporate expenses |
(3,120) |
(2,639) |
(7,937) |
(6,694) |
|
Exploration expenses |
(3,121) |
(1,542) |
(7,641) |
(4,972) |
|
Care and maintenance expenditures |
(2) |
(39) |
(16) |
(46) |
|
Other income |
1,549 |
426 |
2,860 |
992 |
|
EBITDA |
90,139 |
30,717 |
216,327 |
138,309 |
|
Depreciation/amortisation |
(16,245) |
(13,985) |
(45,001) |
(39,780) |
|
Net foreign exchange (loss)/gain |
685 |
77 |
3,815 |
(5,879) |
|
Net finance (cost)/income |
687 |
(2,880) |
889 |
(2,961) |
|
Tax |
(12,398) |
(3,081) |
(29,154) |
(18,777) |
|
Profit for the period |
62,868 |
10,848 |
146,876 |
70,912 |
Three months financial review
Revenues for the three-month period ended 30 September 2026 amounted to €187.8 million (Q3 2025: €106.8 million). The increase in revenues was mainly due to higher realised copper prices and higher volumes of copper concentrate sold, supported by higher production from improved recoveries and a reduction of concentrate inventories.
Realised prices excluding quotation periods (“QPs”) were US$6.44/lb copper during Q3 2026 compared with US$4.41/lb in Q3 2025. The realised price including QPs was approximately US$6.24/lb during Q3 2026 (Q3 2025: US$4.38/lb).
Cost of sales for the three-month period ended 30 September 2026 amounted to €92.9 million, compared with €72.2 million in Q3 2025. The increase primarily reflected higher mining costs, driven by higher diesel prices and the use of specialised explosives in high-sulphur areas. Higher electricity prices during the quarter and higher offsite costs also contributed to the increase.
Cash costs were US$2.89/lb payable copper during Q3 2026 compared with US$2.55/lb in the same period last year, primarily due to higher offsite costs and lower silver revenue, including an unfavourable settlement adjustment on prior silver sales. Higher mining costs were mainly due to higher diesel prices and the use of specialised explosives in high-sulphur areas. Together with higher electricity prices, these pressures were largely offset on a per-pound basis by higher payable copper production. AISC for Q3 2026, excluding one-off investments in the tailings dam and San Dionisio stripping, was US$3.34/lb payable copper compared with US$2.98/lb in Q3 2025. The increase primarily reflected higher cash costs and sustaining capital expenditure.
Sustaining capex for Q3 2026 amounted to €2.4 million (Q3 2025: €0.4 million), mainly related to the new crusher and enhancements in the processing systems. In addition, the Company continues to invest in the tailings dam project storage capacity, having invested €1.7 million in Q3 2026 (Q3 2025: €3.5 million). Capitalised stripping costs for Cerro Colorado during Q3 2026 amounted to €5.1 million (Q3 2025: €3.9 million) and capex associated with the San Dionisio area amounted to €10.2 million (Q3 2025: €7.9 million).
Corporate expenses amounted to €3.1 million (Q3 2025: €2.6 million) and include non-operating costs of the Cyprus office, legal and consultancy fees, listing costs, directors’ and officers’ emoluments, and corporate office salaries and administrative expenses.
Exploration costs on Atalaya’s project portfolio for Q3 2026 were €3.1 million, compared to €1.5 million in Q3 2025, mainly due to activities in the Skellefte Belt and Rockliden Projects in Sweden.
Care and maintenance costs were €2k for the three-month period ended 30 September 2026 (Q3 2025: €39k).
Other income represented €1.5 million, compared to €0.4 million in Q3 2025, mainly due to the recognition of services provided to Lain related to the E-LIX project.
EBITDA for the three months ended 30 September 2026 amounted to €90.1 million, compared to €30.7 million in Q3 2025. The higher EBITDA primarily reflected higher sales volumes and realised copper prices, partially offset by higher operating costs.
Depreciation and amortisation for the quarter totalled €16.2 million (Q3 2025: €14.0 million).
Net foreign exchange gain of €0.7 million mainly arose from the settlement and revaluation of US Dollar-denominated balances during the quarter.
Net finance income for Q3 2026 was €0.7 million, compared with a cost of €2.9 million in the same period in 2025. Finance cost for Q3 2025 included an impairment of €2.7 million for a loan to Lain Technologies in relation to the E-LIX pilot plant.
Nine months financial review
Revenues for the nine-month period ended 30 September 2026 amounted to €452.5 million (YTD 2025: €361.5 million). The increase in revenues was mainly due to higher realised copper prices and lower treatment and refining charges, partially offset by lower volumes of copper concentrate sold and a lower concentrate grade.
Copper concentrate production during the nine-month period was 223,287 tonnes (YTD 2025: 231,706 tonnes), with 224,078 tonnes of copper concentrate sold (YTD 2025: 245,429 tonnes). Inventories of concentrates at the reporting date were 3,259 tonnes (4,050 tonnes as at 31 December 2025).
Copper contained in concentrates sold was 37,491 tonnes in YTD 2026 (YTD 2025: 41,664 tonnes).
Realised copper prices excluding QPs for YTD 2026 were US$6.19/lb, compared with US$4.31/lb in YTD 2025. The realised price remained close to the market average, which was US$6.09/lb in YTD 2026 versus US$4.33/lb in YTD 2025. No hedging agreements were entered into during the period.
Cost of sales amounted to €223.4 million in YTD 2026 (YTD 2025: €212.5 million). The increase primarily reflected higher mining costs, driven by higher diesel prices and the use of specialised explosives in high-sulphur areas, together with higher offsite costs and higher freight prices. These increases were partly offset by a smaller reduction in concentrate inventories than in YTD 2025, when more stock from previous periods was sold and its production costs were recognised in cost of sales.
Cash costs were US$2.60/lb payable copper, compared with US$2.33/lb in YTD 2025. The increase mainly reflected higher mining costs, driven by higher diesel prices and the use of specialised explosives in high-sulphur areas, together with higher offsite costs and higher freight rates. A stronger euro against the US dollar also contributed to the increase by raising the US dollar equivalent of euro-denominated costs. These factors were partially offset by higher silver credits and lower treatment and refining charges. AISC, excluding investment in tailings dam and San Dionisio stripping, was US$3.11/lb payable copper (YTD 2025: US$2.84/lb), reflecting higher cash costs, sustaining capital and corporate costs, partially offset by lower capitalised stripping.
Sustaining capex for YTD 2026 totalled €4.5 million compared with €3.3 million in YTD 2025, mainly related to the new crusher and enhancements in the plant’s processing systems. Investment in the tailings dam amounted to €6.9 million, compared with €15.8 million in YTD 2025. Stripping costs capitalised for Cerro Colorado during YTD 2026 amounted to €17.1 million (YTD 2025: €21.0 million).
Capex for San Dionisio area was €26.2 million in YTD 2026 (YTD 2025: €13.1 million).
Corporate costs for YTD 2026 were €7.9 million (YTD 2025: €6.7 million), mainly comprising the Company’s overhead expenses.
Exploration costs totalled €7.6 million (YTD 2025: €5.0 million), mainly due to activities in the Skellefte Belt and Rockliden Projects in Sweden and Proyecto Masa Valverde.
EBITDA for the nine months ended 30 September 2026 amounted to €216.3 million (YTD 2025: €138.3 million).
Depreciation and amortisation for YTD 2026 totalled €45.0 million (YTD 2025: €39.8 million).
Net foreign exchange gain was €3.8 million (YTD 2025: loss of €5.9 million).
Net finance income for YTD 2026 amounted to €0.9 million, compared with a cost of €3.0 million in YTD 2025, which mainly included a €2.7 million impairment charge on the loan to Lain Technologies relating to the E-LIX pilot plant.
Copper prices
The average realised copper price (excluding QPs) increased by 46% to US$6.44/lb in Q3 2026, from US$4.41/lb in Q3 2025.
The average prices of copper for the three and nine month period ended 30 September 2026 and 2025 are summarised below:
|
US$/lb |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Realised copper price (excluding QPs) |
6.44 |
4.41 |
6.19 |
4.31 |
|
Market copper price per lb (period average) |
6.41 |
4.31 |
6.09 |
4.33 |
Realised copper prices for the reporting period noted above have been calculated using payable copper and excluding both provisional invoices and final settlements of QPs together. The realised price during Q3 2026, including the QP, was approximately US$6.24/lb.
- Non-GAAP Measures
Atalaya has included certain non-IFRS measures including “EBITDA”, “Cash Costs per pound of payable copper”, “All-In Sustaining Costs” (“AISC”) “realised prices” and “Net Cash/Debt” in this report. Non-IFRS measures do not have any standardised meaning prescribed under IFRS, and therefore they may not be comparable to similar measures presented by other companies. These measures are intended to provide additional information and should not be considered in isolation or as a substitute for indicators prepared in accordance with IFRS.
EBITDA includes gross sales net of penalties and discounts and all operating costs, excluding finance, tax, impairment, depreciation and amortisation expenses. Cash Costs per pound of payable copper includes cash operating costs, including treatment and refining charges (“TC/RC”), freight and distribution costs net of by-product credits. Cash Costs per pound of payable copper is consistent with the widely accepted industry standard established by Wood Mackenzie and is also known as the C1 Cash Costs.
AISC per pound of payable copper includes C1 Cash Costs plus royalties and agency fees, expenditures on rehabilitation, capitalised stripping costs, exploration and geology costs, corporate costs and recurring sustaining capital expenditures but excludes one-off sustaining capital projects, such as the tailings dam project.
Realised price per pound of payable copper is the value of the copper payable included in the concentrate produced including the discounts and other features governed by the offtake agreements of the Group and all discounts or premiums provided in commodity hedge agreements with financial institutions if any, expressed in USD per pound of payable copper. Realised prices do not include period end mark to market adjustments in respect of provisional pricing. Realised price is consistent with the widely accepted industry standard definition.
Net cash represents cash and cash equivalents less current and non-current bank borrowings. Lease liabilities are excluded from this measure.
- Liquidity and Capital Resources
Atalaya monitors factors that could impact its liquidity as part of Atalaya’s overall capital management strategy. Factors that are monitored include, but are not limited to, the market price of copper, foreign currency rates, production levels, operating costs, capital and administrative costs.
The following is a summary of Atalaya’s cash position and cash flows as at 30 September 2026 and 31 December 2025.
Liquidity information
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
|
|
|
|
|
Unrestricted cash and cash equivalents at Group level |
331,256 |
146,505 |
|
Unrestricted cash and cash equivalents at Operation level |
22,819 |
19,801 |
|
Consolidated cash and cash equivalents |
354,075 |
166,306 |
|
Net cash position (1) |
342,139 |
121,960 |
|
Working capital surplus |
333,116 |
93,822 |
|
|
|
|
(1) Includes borrowings
Unrestricted cash and cash equivalents, which include balances held at both Group and Operation levels, increased to €354.1 million as at 30 September 2026, up from €166.3 million at 31 December 2025. This increase was primarily driven by cash inflows from the January 2026 capital increase and strong positive operating cash flows generated during the period, partially offset by investment outflows. At the Group level, cash rose from €146.5 million to €331.3 million, while Operation level cash increased from €19.8 million to €22.8 million.
The Group generated net cash from operating activities of €165.6 million in YTD 2026, supported by strong operating performance, partly offset by working capital outflows, mainly related to higher trade and other receivables. Investing activities used €69.7 million, principally for the investment in Lara Exploration Ltd., San Dionisio development, tailings dam expansion and processing upgrades. Financing activities generated a net inflow of €93.4 million, primarily reflecting net equity proceeds of €144.9 million, partly offset by net borrowing repayments of €32.4 million and dividend payments of €18.5 million.
As of 30 September 2026, the Group reported a working capital surplus of €333.1 million, compared with €93.8 million at 31 December 2025. The improvement in working capital reflects a stronger cash position. The Group also maintained a net cash position of €342.1 million, up from €122.0 million at 31 December 2025, underscoring its solid liquidity profile.
Overview of the Group’s cash flows
|
(Euro 000’s) |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Cash flows from operating activities |
56,995 |
41,729 |
165,555 |
120,006 |
|
Cash flows used in investing activities |
(19,784) |
(17,992) |
(69,740) |
(59,765) |
|
Cash flows from/(used in) financing activities |
(38,713) |
(12,863) |
93,378 |
2,026 |
|
Net (decrease)/increase in cash and cash equivalents |
(1,502) |
10,874 |
189,193 |
62,267 |
|
Net foreign exchange differences |
5,295 |
(77) |
(1,424) |
(1,335) |
|
Total net cash flow for the period |
3,793 |
10,797 |
187,769 |
60,932 |
Three months cash flows review
Total net cash inflow for the three months ended 30 September 2026 was €3.8 million. Cash from operating activities amounted to €57.0 million, while investing activities consumed €19.8 million and financing activities resulted in a net outflow of €38.7 million. These movements resulted in a €1.5 million decrease in cash before positive foreign exchange movements of €5.3 million.
Cash generated from operations before changes in working capital was €94.8 million. During the quarter, inventories decreased by €6.2 million, trade and other receivables increased by €52.2 million, and trade and other payables increased by €11.1 million, resulting in a net working capital outflow.
Investing activities consumed €19.8 million, mainly related to ongoing development works at the tailing dams, the San Dionisio deposit and continued upgrades to processing infrastructure.
Financing activities resulted in a net cash outflow of €38.7 million, primarily reflecting net borrowing repayments of €20.0 million, dividend payments of €18.5 million, lease payments of €0.2 million and share issuance costs of €0.1 million.
Nine months cash flow review
For the nine months ended 30 September 2026, the Group reported a net cash inflow of €187.8 million. This included net cash from operating activities of €165.6 million, investing outflows of €69.7 million, net financing inflows of €93.4 million and negative foreign exchange differences of €1.4 million.
Cash generated from operations before working capital movements was €223.3 million. Working capital movements resulted in a net outflow, driven by a €50.9 million increase in trade and other receivables and a €3.2 million increase in inventories, partly offset by a €9.4 million increase in trade and other payables.
Cash outflows from investing activities of €69.7 million mainly reflect the investment in Lara Exploration Ltd. and capital expenditure related to the San Dionisio area, tailings storage facilities and processing plant upgrades.
Financing activities resulted in a net inflow of €93.4 million, mainly reflecting the equity offering, which generated gross proceeds of €150.2 million, partly offset by share issuance costs of €5.3 million, net borrowing outflows of €32.4 million, dividend payments of €18.5 million and lease payments of €0.5 million.
Foreign exchange
Foreign exchange rate movements can have a significant effect on Atalaya’s operations, financial position and results. Atalaya’s sales are denominated in U.S. dollars (“USD”), while Atalaya’s operating expenses, income taxes and other expenses are mainly denominated in Euros (“EUR”) which is the functional currency of the Group, and to a much lesser extent in British Pounds (“GBP”).
Accordingly, fluctuations in the exchange rates can potentially impact the results of operations and carrying value of assets and liabilities on the balance sheet.
Exchange rate movements increased cash and cash equivalents by €5.3 million during Q3 and decreased €1.4 million in YTD 2026, respectively, primarily reflecting decrease in foreign currency cash balance.
The following table summarises the movement in key currencies versus the EUR:
|
|
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Average rates for the periods |
|
|
|
|
|
GBP – EUR |
0.8560 |
0.8506 |
0.8633 |
0.8663 |
|
USD – EUR |
1.1505 |
1.1681 |
1.1610 |
1.1188 |
|
Spot rates as at |
|
|
|
|
|
GBP – EUR |
0.8546 |
0.8734 |
0.8546 |
0.8734 |
|
USD – EUR |
1.1355 |
1.1741 |
1.1355 |
1.1741 |
- Sustainability
Corporate Social Responsibility
Atalaya continued its commitment to social investment through Fundación Atalaya during the third quarter of 2026, supporting initiatives focused on local infrastructure, education, environmental conservation, sports and culture across the Cuenca Minera region.
Collaboration with local municipalities remained a key area of activity. In Minas de Riotinto, Fundación Atalaya supported the refurbishment of Children’s playgrounds in Los Cantos neighbourhood and improvements to the Municipal Food Market. In Nerva, the foundation collaborated on several infrastructure projects, including road resurfacing, modernisation of street furniture and removal of architectural barriers to improve accessibility. Additional support was provided for the refurbishment of facilities at the municipal football stadium.
Environmental initiatives also featured during the quarter. In Berrocal, Fundación Atalaya supported the installation of wildlife feeders and water stations, as well as an educational project at CEIP La Picota involving the production of honey sweets to raise funds for local reforestation activities.
The foundation also maintained its support for local sports through sponsorship of Nerva Football Club and its youth football academy, contributing to the development of grassroots sports in the region.
Cultural activities included sponsorship of the XXIV Outdoor Painting Competition “Villa de Nerva”, bringing together artists to capture the town’s landscapes and heritage. Atalaya also supported the first “Tierra Abierta” Outdoor Painting Competition in Minas de Riotinto, an initiative focused on the area’s mining landscapes.
Health and Safety
Accident figures continued to improve in the third quarter of 2026 compared with previous quarters, enabling us to end the third quarter with a frequency rate (FR) of 4.32, which is close to the target figure for 2026 (4.02) and a severity rate (SR) of 0.15, meeting the established target limit (0.20). In the third quarter, there were two minor accidents resulting in lost working days at contractor companies.
Regarding Occupational Health, all the measurements planned for this period were carried out in the third quarter: crystalline silica and respirable dust, whole-body vibrations, five-yearly electromagnetic field assessments and thermal stress. Fit testing of respiratory protective equipment continued amongst ARM’s workforce.
As for the First Response Team, the specific training sessions planned for the third quarter were carried out: extrication of people from vehicles.
Random checks for psychoactive substances (alcohol and other drugs) have continued at the entrance and in the infirmary. In the third quarter, two people were prevented from working whilst under the influence of psychoactive substances.
In relation to the Zero Harm Challenge project, in the third quarter two proposals from the “Cuando Nadie Te Ve” programme, out of the four working groups, were finalised and submitted to management prior to their launch.
In the third quarter, the “Safety Points” campaign was launched and is now underway to raise awareness amongst workers, both at Atalaya and, above all, amongst those from contractor companies. This campaign involves each worker being allocated 5 safety points, which they must not lose. These points are lost for breaches of procedures or for failing to use PPE correctly. Anyone who loses all five points will be barred from entering the site for three days, which constitutes an internal disciplinary measure on safety grounds.
Similarly, the health and wellbeing messages issued by the nursing department over the last three months have been: “Look after your brain, it’s your engine”, “Consequences of self-medication” and “Information on Alzheimer’s”. The nursing department, together with the IT department, is developing an app to digitise information on all medical attendances, whether due to common illness or work-related accidents.
It should be noted that on-site leadership activities are continuing, with a compliance rate of 96.7% in the third quarter, an increase of 6.0 percentage points from Q2 2026.
Regarding psychosocial factors, the process of reviewing the psychosocial risk assessment has begun; as on the previous occasion, the CoPsoQ ISTAS-2 methodology was chosen, comprising 20 psychosocial dimensions, and involving a participatory and joint approach. During this quarter, the working group was set up; it met and defined how the process would be carried out and launched the survey.
The statutory audit on occupational risk prevention was successfully completed in September, with positive results and no non-conformities identified in occupational health and safety management.
A Joint Prevention Service has been set up with the companies Atalaya Riotinto Minera, SLU and Atalaya Mining Copper, SA, and the in-house prevention service will cease to operate from 1 October.
Finally, it should be noted that work continues on occupational health and safety at Atalaya Masa Valverde, with the development of specific procedures, job evaluations and plans for a first-aid room in order to apply for the relevant healthcare accreditation. It is worth highlighting that, since June, a nurse has been available 12 hours a day from Monday to Saturday, coinciding with the full duration of the works.
Environment
During the third quarter of 2026, the Environmental Department has continued advancing its environmental monitoring and natural resource management initiatives. Key points of the quarter:
During the third quarter of the year, two environmental incidents were registered: A fire outbreak was detected in the Cerro Colorado area. The supervisor who detected the situation dispatched a water truck to the zone, immediately extinguishing the fire outbreak.
A mineral oil spill occurred in the mining workshop area. The incident took place when a dumper collided with some IBCs located in the outdoor area of the workshops. The area supervisor proceeded to collect the waste and clean the area.
A total rainfall of 3.0 l/m2 was recorded in Q3 2026, which was around 44% less than in the same period of previous year. Furthermore, the total rain collected for the hydrological year (October 2025 to September 2026) is 688.0 l/m2, which is a 36% less that the rainfall recorded in the previous hydrological year (same period).
On 13 July, The Decommissioning Project for ARM’s Former Gold/ “Copper Line” was submitted.
On 16 July, the occupation of a public land was requested to the Mining Project for a fresh water pipeline from the “Aguas Limpias” reservoir.
29 July, a Non- Substantial Modification of the environmental permit was requested because of the actions defined in the project “Complementary actions for reinforcement and integration into the environment of the Riotinto tailings storage facility”.
The additional measures contemplated in the action plan against dust continued to be implemented, intensifying periodic irrigation, implementing new coordination measures, and carrying out exhaustive monitoring of the emissions generated in the operation.
The Environmental Department continues working in the Restoration Plan in both areas, operational and historical.
All the regular internal controls of diffuse emissions into the atmosphere have been carried out, and the results of the controls were within the limit values. The rest of the periodic and mandatory controls have been carried out without any incidents. In addition, during the quarter, several reports were sent to the Administration bodies.
Environmental inspections were performed daily, mainly focused on chemical storage and handling, waste management, uncontrolled releases and environmentally practices carried out in the project of ARM’s workforce and contractor companies. Additionally, dust control and drainage system inspections were performed regularly. 89 inspections were carried out in total during the third quarter, including plant, mine area and the contractor’s camps.
- Risk Factors
Due to the nature of Atalaya’s business in the mining industry, the Group is subject to various risks that could materially impact the future operating results and could cause actual events to differ materially from those described in forward-looking statements relating to Atalaya. Readers are encouraged to read and consider the risk factors detailed in Atalaya’s audited, consolidated financial statements for the year ended 31 December 2025.
The Company continues to monitor the principal risks and uncertainties that could materially impact the Company’s results and operations, including the areas of increasing uncertainty such as the impact of macro-economic uncertainty on the business and geopolitical developments or the risks inherent in the development of new technologies.
In particular, Atalaya continues to monitor the risks associated with its investment in the ELIX technology together with Lain Technologies Ltd (“Lain”). Although the E-LIX technology has been performing broadly in line with the design parameters, progress towards achieving sustainable, commercially viable throughput levels has been slower and more challenging than originally anticipated due to operational bottlenecks identified at the Industrial Plant (Note 8). The Group continues to assess the operational and commercial outlook for the technology and the recoverability of related assets.
Management reassessed the carrying amounts of the E-LIX-related assets at 30 September 2026 and concluded that no additional impairment or reversal of impairment was required. The fair value of the Convertible Loan also remained unchanged.
- Critical accounting policies, estimates, judgements, assumptions and accounting changes
The preparation of Atalaya’s Financial Statements in accordance with IFRS requires management to make estimates, judgements and assumptions that affect amounts reported in the Financial Statements and accompanying notes. There is a full discussion and description of Atalaya’s critical accounting policies in the Audited Consolidated Financial Statements for the year ended 31 December 2025.
As at 30 September 2026, there are no significant changes in critical accounting policies or estimates to those applied in 2025. We highlight the assumptions made in relation to Lain Technologies and the progress on the Industrial Plant in Note 8.
- Other Information
Additional information about Atalaya Mining Copper, S.A. is available at www.atalayamining.com
Unaudited Condensed Consolidated Interim Financial Statements on subsequent pages.
By Order of the Board of Directors,
Neil Gregson
Chair
Sevilla, 11 November 2026
Condensed Consolidated Interim Statement of Comprehensive Income
(All amounts in Euro thousands unless otherwise stated)
For the period ended 30 September 2026 and 2025
|
(Euro 000’s) |
Note |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
|
|
(Unaudited and unreviewed) |
(Unaudited and unreviewed) |
(Unaudited) |
(Unaudited) |
|
Revenue |
4 |
187,766 |
106,753 |
452,457 |
361,503 |
|
Operating costs and mine site administrative expenses |
(88,259) |
(71,122) |
(216,388) |
(210,817) |
|
|
Mine site depreciation and amortisation |
|
(16,245) |
(13,985) |
(45,001) |
(39,780) |
|
Gross profit |
|
83,262 |
21,646 |
191,068 |
110,906 |
|
Administration and other expenses |
|
(3,120) |
(2,639) |
(7,937) |
(6,694) |
|
Share-based benefits |
17 |
(4,674) |
(1,120) |
(7,008) |
(1,657) |
|
Exploration expenses |
|
(3,121) |
(1,542) |
(7,641) |
(4,972) |
|
Care and maintenance expenditure |
|
(2) |
(39) |
(16) |
(46) |
|
Other income |
|
1,549 |
426 |
2,860 |
992 |
|
Operating profit |
|
73,894 |
16,732 |
171,326 |
98,529 |
|
Net foreign exchange (loss)/gain |
|
685 |
77 |
3,815 |
(5,879) |
|
Net finance income/(costs) |
5 |
687 |
(2,880) |
889 |
(2,961) |
|
Profit before tax |
|
75,266 |
13,929 |
176,030 |
89,689 |
|
Tax |
6 |
(12,398) |
(3,081) |
(29,154) |
(18,777) |
|
Profit for the period |
|
62,868 |
10,848 |
146,876 |
70,912 |
|
|
|
|
|
|
|
|
Profit for the period attributable to: |
|
|
|
|
|
|
- Owners of the parent |
7 |
62,941 |
10,925 |
147,054 |
71,073 |
|
- Non-controlling interests |
|
(73) |
(77) |
(178) |
(161) |
|
|
|
62,868 |
10,848 |
146,876 |
70,912 |
|
|
|
|
|
|
|
|
Earnings per share from operations attributable to equity holders of the parent during the period: |
|
|
|
|
|
|
Basic earnings per share (EUR cents per share) |
7 |
40.9 |
7.8 |
96.4 |
50.5 |
|
Fully diluted earnings per share (EUR cents per share) |
7 |
39.2 |
7.4 |
92.4 |
48.5 |
|
|
|
|
|
|
|
|
Profit for the period |
|
62,868 |
10,848 |
146,876 |
70,912 |
|
Other comprehensive income: |
|
- |
- |
- |
- |
|
Other comprehensive income that will not be reclassified to profit or loss in subsequent periods (net of tax): |
|
|
|
|
|
|
Change in fair value of financial assets through other comprehensive income ‘OCI’ |
(253) |
29 |
1,593 |
29 |
|
|
Total comprehensive income for the period |
62,615 |
10,877 |
148,469 |
70,941 |
|
|
|
|
|
|
|
|
|
Total comprehensive income for the period attributable to: |
|
|
|
|
|
|
- Owners of the parent |
7 |
62,688 |
10,954 |
148,647 |
71,102 |
|
- Non-controlling interests |
|
(73) |
(77) |
(178) |
(161) |
|
|
|
62,615 |
10,877 |
148,469 |
70,941 |
The notes on the subsequent pages are an integral part of these Unaudited Condensed Consolidated Interim Financial Statements.
Condensed Consolidated Interim Statement of Financial Position
(All amounts in Euro thousands unless otherwise stated)
As at 30 September 2026 and 31 December 2025
|
(Euro 000’s) |
Note |
30 Sep 2026 |
31 Dec 2025 |
|
Assets |
|
Unaudited |
Audited |
|
Non-current assets |
|
|
|
|
Property, plant and equipment |
8 |
466,792 |
447,729 |
|
Intangible assets |
9 |
78,715 |
74,919 |
|
Loans |
13 |
9,725 |
9,725 |
|
Trade and other receivables |
12 |
5,803 |
1,122 |
|
Non-current financial assets |
2.3 |
11,718 |
1,101 |
|
Deferred tax asset |
|
17,635 |
15,840 |
|
|
|
590,388 |
550,436 |
|
Current assets |
|
|
|
|
Inventories |
10 |
34,104 |
30,871 |
|
Loans |
13 |
- |
20 |
|
Trade and other receivables |
12 |
92,584 |
41,113 |
|
Tax refundable |
|
2,418 |
2,834 |
|
Other financial assets |
2.3 |
31 |
62 |
|
Cash and cash equivalents |
15 |
354,075 |
166,306 |
|
|
|
483,212 |
241,206 |
|
Total assets |
|
1,073,600 |
791,642 |
|
|
|
|
|
|
Equity and liabilities |
|
|
|
|
Equity attributable to owners of the parent |
|
|
|
|
Share capital |
16 |
13,838 |
12,668 |
|
Share premium |
16 |
465,635 |
321,856 |
|
Other reserves |
17 |
141,363 |
89,255 |
|
Accumulated profit |
|
246,659 |
166,091 |
|
|
|
867,495 |
589,870 |
|
Non-controlling interests |
|
1,762 |
1,940 |
|
Total equity |
|
869,257 |
591,810 |
|
|
|
|
|
|
Liabilities |
|
|
|
|
Non-current liabilities |
|
|
|
|
Trade and other payables |
18 |
14,756 |
14,142 |
|
Provisions |
19 |
29,813 |
28,764 |
|
Lease liabilities |
21 |
3,362 |
3,834 |
|
Borrowings |
20 |
6,316 |
5,708 |
|
|
|
54,247 |
52,448 |
|
Current liabilities |
|
|
|
|
Trade and other payables |
18 |
123,040 |
106,117 |
|
Lease liabilities |
21 |
632 |
639 |
|
Borrowings |
20 |
5,620 |
38,638 |
|
Dividend payable |
11 |
8 |
8 |
|
Current provisions |
19 |
2,121 |
1,845 |
|
Current tax liabilities |
|
18,675 |
136 |
|
|
|
150,096 |
147,384 |
|
Total liabilities |
|
204,343 |
199,832 |
|
Total equity and liabilities |
|
1,073,600 |
791,642 |
The notes on the subsequent pages are an integral part of these Unaudited Condensed Consolidated Interim Financial Statements.
Condensed Consolidated Interim Statement of Changes in Equity
(All amounts in Euro thousands unless otherwise stated)
For the period ended 30 September 2026 and 2025
|
(Euro 000’s) |
Note |
Share capital |
Share premium |
Other reserves |
Accum. profits |
Total |
NCI |
Total equity |
|
(Unaudited) |
|
|||||||
|
At 1 January 2026 |
|
12,668 |
321,856 |
89,255 |
166,091 |
589,870 |
1,940 |
591,810 |
|
Profit for the period |
|
- |
- |
- |
147,054 |
147,054 |
(178) |
146,876 |
|
Change in fair value of financial assets through OCI |
|
- |
- |
1,593 |
- |
1,593 |
- |
1,593 |
|
Total comprehensive income |
|
- |
- |
1,593 |
147,054 |
148,647 |
(178) |
148,469 |
|
Issuance of share capital |
16 |
1,170 |
149,079 |
- |
- |
150,249 |
- |
150,249 |
|
Share issue costs |
|
- |
(5,300) |
- |
- |
(5,300) |
- |
(5,300) |
|
Recognition of depletion factor |
17 |
- |
- |
21,271 |
(21,271) |
- |
- |
- |
|
Recognition of share-based payments |
17 |
- |
- |
2,479 |
- |
2,479 |
- |
2,479 |
|
Recognition of non-distributable reserve |
17 |
- |
- |
6,861 |
(6,861) |
- |
- |
- |
|
Recognition of distributable reserve |
17 |
- |
- |
19,583 |
(19,583) |
- |
- |
- |
|
Other changes in equity |
|
- |
- |
321 |
(321) |
- |
- |
- |
|
Dividends |
11 |
- |
- |
- |
(18,450) |
(18,450) |
- |
(18,450) |
|
At 30 September 2026 |
|
13,838 |
465,635 |
141363 |
246,659 |
867,495 |
1,762 |
869,257 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(Euro 000’s) |
Note |
Share capital |
Share premium |
Other reserves |
Accum. profits |
Total |
NCI |
Total equity |
|
(Unaudited) |
|
|||||||
|
At 1 January 2025 |
|
12,668 |
321,856 |
88,774 |
93,085 |
516,383 |
2,154 |
518,537 |
|
Profit for the period |
|
- |
- |
- |
71,073 |
71,073 |
(161) |
70,912 |
|
Change in fair value of financial assets through OCI |
|
- |
- |
29 |
- |
29 |
- |
29 |
|
Total comprehensive income |
|
- |
- |
29 |
71,073 |
71,102 |
(161) |
70,941 |
|
Recognition of share-based payments |
17 |
- |
- |
1,657 |
- |
1,657 |
- |
1,657 |
|
Recognition of non-distributable reserve |
17 |
- |
- |
685 |
- |
685 |
- |
685 |
|
Recognition of distributable reserve |
17 |
- |
- |
(670) |
- |
(670) |
- |
(670) |
|
Dividends |
11 |
- |
- |
- |
(10,064) |
(10,064) |
- |
(10,064) |
|
At 30 September 2025 |
|
12,668 |
321,856 |
90,341 |
154,216 |
579,081 |
1,993 |
581,074 |
|
|
|
|
|
|
|
|
|
|
The notes on subsequent pages are an integral part of these Unaudited Condensed Consolidated Interim Financial Statements.
Condensed Consolidated Interim Cash Flow Statement
(All amounts in Euro thousands unless otherwise stated)
For the period ended 30 September 2026 and 2025
|
(Euro 000’s) |
Note |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
||
|
|
|
(Unaudited and unreviewed) |
(Unaudited and unreviewed) |
(Unaudited) |
(Unaudited) |
||
|
Cash flows from operating activities |
|
|
|
|
|
||
|
Profit before tax |
|
75,266 |
13,929 |
176,030 |
89,689 |
||
|
Adjustments for: |
|
|
|
|
|
||
|
Depreciation of property, plant and equipment |
8 |
15,216 |
12,580 |
41,931 |
35,672 |
||
|
Amortisation of intangibles |
9 |
1,029 |
1,406 |
3,070 |
4,109 |
||
|
Recognition of share-based payments |
17 |
4,674 |
1,120 |
7,008 |
1,657 |
||
|
Interest income |
5 |
(1,152) |
(518) |
(2,362) |
(1,872) |
||
|
Interest expense |
5 |
197 |
555 |
682 |
1,515 |
||
|
Unwinding of discounting on mine rehabilitation provision |
19 |
268 |
141 |
791 |
616 |
||
|
Other tax provision |
19 |
- |
4,692 |
- |
4,692 |
||
|
Impairment loss on fina ncial assets |
|
- |
2,702 |
- |
2,702 |
||
|
Net foreign exchange differences |
|
(685) |
(77) |
(3,815) |
5,879 |
||
|
Unrealised foreign exchange loss on financing activities |
|
- |
1 |
- |
15 |
||
|
Cash inflows from operating activities before working capital changes |
|
94,813 |
36,531 |
223,335 |
144,674 |
||
|
Changes in working capital: |
|
|
|
|
|
||
|
Inventories |
10 |
6,202 |
523 |
(3,182) |
12,292 |
||
|
Trade and other receivables |
12 |
(52,237) |
(2,047) |
(50,900) |
(31,305) |
||
|
Trade and other payables |
18 |
11,092 |
7,230 |
9,403 |
4,081 |
||
|
Loans |
|
- |
- |
20 |
- |
||
|
Deferred consideration |
|
(52) |
- |
(1,794) |
- |
||
|
Provisions |
19 |
371 |
(64) |
248 |
(584) |
||
|
Cash flows from operations |
|
60,189 |
42,173 |
177,131 |
129,158 |
||
|
Tax paid |
|
(2,715) |
- |
(10,612) |
(7,970) |
||
|
Interest on leases liabilities |
5 |
(4) |
- |
(11) |
- |
||
|
Interest paid |
5 |
(475) |
(444) |
(953) |
(1,182) |
||
|
Net cash from operating activities |
|
56,995 |
41,729 |
165,555 |
120,006 |
||
|
|
|
|
|
|
|
||
|
Cash flows from investing activities |
|
|
|
|
|
||
|
Purchase of property, plant and equipment |
8 |
(19,167) |
(16,078) |
(56,771) |
(49,894) |
||
|
Purchase of intangible assets |
9 |
(1,960) |
(2,617) |
(6,866) |
(7,369) |
||
|
Payments for investments |
|
- |
176 |
(8,465) |
(3,370) |
||
|
Interest received |
5 |
1,343 |
527 |
2,362 |
868 |
||
|
Net cash used in investing activities |
|
(19,784) |
(17,992) |
(69,740) |
(59,765) |
||
|
|
|
|
|
|
|
||
|
Cash flows from financing activities |
|
|
|
|
|
||
|
Lease payments |
21 |
(159) |
(129) |
(479) |
(388) |
||
|
Proceeds from borrowings |
20 |
- |
5,336 |
18,483 |
25,069 |
||
|
Repayment of borrowings |
20 |
(20,000) |
(14,209) |
(50,894) |
(18,794) |
||
|
Proceeds from issuance of shares |
16 |
- |
- |
150,249 |
- |
||
|
Payments for share issuance costs |
|
(105) |
- |
(5,300) |
- |
||
|
Share option expense |
|
- |
- |
(232) |
- |
||
|
Dividends |
|
(18,450) |
(3,861) |
(18,450) |
(3,861) |
||
|
Net cash from/(used in) financing activities |
|
(38,713) |
(12,863) |
93,378 |
2,026 |
||
|
|
|
|
|
|
|
||
|
Net increase/(decrease) in cash and cash equivalents |
(1,502) |
10,874 |
189,193 |
62,267 |
|||
|
Net foreign exchange difference |
|
5,295 |
(77) |
(1,424) |
(1,335) |
||
|
Cash and cash equivalents: |
|
|
|
|
|
||
|
At beginning of the period |
|
350,282 |
103,013 |
166,306 |
52,878 |
||
|
At end of the period |
|
354,075 |
113,810 |
354,075 |
113,810 |
||
The notes on the subsequent pages are an integral part of these Unaudited Condensed Consolidated Interim Financial Statements.
Notes to the Unaudited Condensed Consolidated Interim Financial Statements
(All amounts in Euro thousands unless otherwise stated)
For the period ended 30 September 2026 and 2025
- Incorporation and summary of business
Atalaya Mining Plc was incorporated in Cyprus on 17 September 2004 as a private company with limited liability under the Companies Law, Cap. 113 and was converted to a public limited liability company on 26 January 2005. Its registered office was at 1 Lampousa Street, Nicosia, Cyprus.
The Company was first listed on the Alternative Investment Market (AIM) of the London Stock Exchange in May 2005.
Change of name and share consolidation (2015)
Following the Company’s Extraordinary General Meeting (“EGM”) on 13 October 2015, the change of name from EMED Mining Public Limited to Atalaya Mining Plc became effective on 21 October 2015. On the same day, the consolidation of ordinary shares came into effect, whereby all shareholders received one new ordinary share of nominal value Stg £0.075 for every 30 existing ordinary shares of nominal value Stg £0.0025. The Company’s trading symbol became “ATYM”.
On 29 April 2024, the Company was admitted to trading on the main market of the London Stock Exchange.
Cross-border conversion (re-domiciliation) (2024-2025)
On 10 January 2025, the Company successfully completed a cross-border conversion, resulting in its re-domiciliation from the Republic of Cyprus to the Kingdom of Spain. This process was carried out in accordance with the Company’s strategic objectives to align its corporate structure with its operational base in Spain.
A cross-border conversion deed was executed on 23 December 2024 and subsequently filed with the Spanish Commercial Registry on 27 December 2024. Under Spanish corporate law, the re-domiciliation became legally effective from the date of registration with the Spanish Commercial Registry, i.e., 27 December 2024. However, for administrative and procedural purposes, the final formalities were completed on 9 January 2025, with the official public announcement being made on 10 January 2025. Following this change:
- Atalaya's corporate seat was transferred from Cyprus to Spain, and Atalaya became a Spanish public limited company (Sociedad Anónima) under the laws of the Kingdom of Spain;
- Atalaya's registered name changed from Atalaya Mining Plc to Atalaya Mining Copper, S.A.; and
- Atalaya's registered address changed from 1, Lampousa
- Street, 1095 Nicosia, Cyprus to Paseo de las Delicias, 1, 3, 41001, Sevilla, Spain.
The Company’s shares commenced trading under “Atalaya Mining Copper, S.A.” on 10 January 2025 at 8:00 am (London time) and the nominal value of the Company’s shares were also adjusted from 7.5p to €0.09 per share.
Principal activities
Atalaya is a European mining and development company. The strategy is to evaluate and prioritise metal production opportunities in several jurisdictions throughout the well-known belts of base and precious metal mineralisation in Spain, elsewhere in Europe and Latin America.
The Group has interests in four mining projects: Proyecto Riotinto, Proyecto Touro, Proyecto Masa Valverde and Proyecto Ossa Morena. In addition, the Group has an earn-in agreement to acquire two investigation permits at Proyecto Riotinto East.
Proyecto Riotinto
The Company owns and operates through a wholly owned subsidiary, “Proyecto Riotinto”, an open-pit copper mine located in the Iberian Pyrite Belt, in the Andalusia region of Spain, approximately 65 km northwest of Seville. A brownfield expansion of this mine was completed in 2019 and successfully commissioned by Q1 2020.
In May 2025, the Junta de Andalucía granted the Unified Environmental Authorisation (AAU) for the San Dionisio deposit, located within the Riotinto District. This authorisation enables the Company to expand its mining activities and supports its strategy to increase copper production by sourcing higher-grade material for processing at the Riotinto plant.
Proyecto Touro
The Group initially acquired a 10% stake in Cobre San Rafael, S.L. (“CSR”), the owner of Proyecto Touro, as part of an earn-in agreement, which was designed to enable the Group to acquire up to 80% of the copper project. Proyecto Touro is located in Galicia, north-west Spain, and is currently in the permitting process.
In July 2017, the Group announced that it had executed the option to acquire 10% of the share capital of CSR, a wholly owned subsidiary of Explotaciones Gallegas S.L. This acquisition was part of an earn-in agreement, structured in four phases, allowing the Group to progressively increase its stake in CSR up to 80%:
- Phase 1 – The Group paid €0.5 million to secure the exclusivity agreement and committed to funding up to a maximum of €5.0 million to support the permitting and financing stages.
- Phase 2 – Upon receipt of permits, the Group is required to pay €2.0 million to acquire an additional 30% interest in the project (cumulative 40%).
- Phase 3 – Once development capital is secured and construction commences, the Group is required to pay €5.0 million to acquire an additional 30% interest in the project (cumulative 70%).
- Phase 4 – Upon declaration of commercial production, the Group will purchase an additional 10% interest (cumulative 80%) in exchange for a 0.75% Net Smelter Return royalty, with a buyback option.
The Agreement was structured to ensure that each phase and corresponding payment would only occur once the project was de-risked, permitted, and operational.
On 24 June 2024, Atalaya announced that Proyecto Touro, via its local entity Cobre San Rafael, was declared a strategic industrial project by the Council of the Xunta de Galicia ("XdG"). Under legislation of the Autonomous Community of Galicia, the status of strategic industrial project (or in Spanish, Proyecto Industrial Estratégico ("PIE")) acts to simplify the administrative procedures associated with the development of industrial projects and intends to substantially reduce permitting timelines.
This declaration highlights the XdG's commitment to promoting new investment that will benefit the region and also support the objectives of the European Union. Copper is considered a strategic raw material by the EU and this project has the potential to become a new source of sustainable European copper production.
The XdG is continuing its review according to the simplified procedures afforded to projects with PIE status. The public information period, which serves to inform the surrounding communities and organisations about the proposed project, concluded on 31 January 2025. At that time, CSR was focused on analysing and responding to feedback from the public and assessing sectoral reports issued by various departments of the XdG.
Following the declaration of Proyecto Touro as a strategic industrial project in June 2024 and subsequent progress in the permitting process, the Group reassessed the probability of completion of phases 2, 3 and 4 under the earn-in agreement. As a result of that reassessment, an intangible asset of €16.5 million was recognised in 2024 in accordance with the Group’s policy on contingent payments, together with the corresponding contingent liabilities.
In accordance with the Group’s policy on non-controlling interests, 20% of this intangible asset was attributed to non-controlling interests.
On 9 October 2026, the European Commission announced the designation of Proyecto Touro as a Strategic Project under the European Union’s Critical Raw Materials Act (“CRMA”). This designation recognises the project’s potential contribution to a secure and sustainable European supply of copper, a strategic raw material essential to electrification, energy infrastructure and industrial development.
Atalaya and its local entity CSR believe that the approval process for the Touro environmental impact statement is nearing completion. Meanwhile, CSR continues to advance early works including detailed engineering and procurement activities.
Proyecto Masa Valverde
On 21 October 2020, the Company announced that it entered into a definitive purchase agreement to acquire 100% of the shares of Cambridge Mineria España, S.L. (since renamed Atalaya Masa Valverde, S.L.U.), a Spanish company which fully owns the Masa Valverde polymetallic project located in Huelva (Spain). Under the terms of the agreement Atalaya would make an aggregate €1.4 million cash payment in two instalments of approximately the same amount: the first upon permitting of the project and the second upon achieving first production from the concession.
In November 2023, the exploitation permit for the Masa Valverde and Majadales deposits was officially granted. Following this milestone, in January 2024, the Company made the first payment of €0.7 million associated with the granted permits.
Masa Valverde has been granted the two key permits required for development, the AAU and the exploitation permit.
During 2026, infill and extensional drilling continued at the Masa Valverde deposit, with two rigs active during the year and additional geotechnical drilling completed. AMV is collaborating with the European Union – funded Explorer Project, focused on drone- based geophysical exploration technologies, including AGG and passive seismic surveys.
Proyecto Ossa Morena
In December 2021, Atalaya announced the acquisition of a 51% interest in Rio Narcea Nickel, S.L., which owned 9 investigation permits. The acquisition also provided a 100% interest in three investigation permits that are also located along the Ossa- Morena Metallogenic Belt. In Q3 2022, Atalaya increased its ownership interest in POM to 99.9%, up from 51%, following completion of a capital increase that will fund exploration activities. During 2022 Atalaya rejected 8 investigation permits.
Atalaya will pay a total of €2.5 million in cash in three instalments and grant a 1% net smelter return (“NSR”) royalty over all acquired permits. The first payment of €0.5 million was made following execution of the purchase agreement. The second and third instalments of €1 million each will be made once the environmental impact statement (“EIS”) and the final mining permits for any project within any of the investigation permits acquired under the Transaction are secured. In accordance with the agreement, these outstanding instalments are disclosed as a non-current payable to the sellers.
Proyecto Riotinto East
In December 2020, Atalaya entered into a Memorandum of Understanding with a local private Spanish company to acquire a 100% beneficial interest in three investigation permits (known as Peñas Blancas, Cerro Negro and Herreros investigation permits), which cover approximately 12,368 hectares and are located immediately east of Proyecto Riotinto. After a short drilling campaign, the Los Herreros investigation permit was rejected in June 2022. Proyecto Riotinto East consists of the remaining two investigation permits, Peñas Blancas and Cerro Negro, totalling 10,016 hectares.
During 2026 a second drill hole was completed at PI Cerro Negro, targeting a coincident gravity and magnetic anomaly. The hole intersected a weak stockwork zone between 110 and 130 metres with minor chalcopyrite clusters. No additional drilling is planned at this stage at Cerro Negro.
At PI Peñas Blancas, drilling remains pending permit approval, while exploration at CE El Palancar is awaiting the completion of the acquisition process.
Skellefte Belt Project and Rockliden Project
In November 2024, the Group entered into agreements with Mineral Prospektering i Sverige AB in relation to the Skellefte Belt Project and the Rockliden Project, both situated in well-established volcanogenic massive sulphide districts renowned for their mineral resource potential.
At the end of Q2 2026, Atalaya completed its Stage 1 funding commitments for the Skellefte Belt Project and has thereby earned a 51% interest.
Investment in Lara Exploration Ltd
On 2 April 2026, Atalaya announced that it had acquired 4,500,000 shares of Lara Exploration Ltd. (TSX-V: LRA) for C$13.5 million. The shares were acquired via private placement at a price of C$3.00 per share and represent approximately 7.3% of Lara's issued and outstanding shares following completion of the private placements as announced by Lara on 1 April 2026. Atalaya acquired the shares for investment purposes.
- Basis of preparation and accounting policies
2.1 Basis of preparation
- Overview
These Condensed Interim Financial Statements are unaudited.
The Unaudited Condensed Consolidated Interim Financial Statements for the period ended 30 September 2026 have been prepared in accordance with International Accounting Standard 34: Interim Financial Reporting. IFRS comprise the standard issued by the International Accounting Standard Board (“IASB”), and IFRS Interpretations Committee (“IFRICs”) as issued by the IASB. Additionally, the Unaudited Condensed Consolidated Interim Financial Statements have also been prepared in accordance with the IFRS as adopted by the European Union (EU), using the historical cost convention and have been prepared on a historical cost basis except for the revaluation of certain financial instruments that are measured at fair value at the end of each reporting period, as explained below.
These Unaudited Condensed Consolidated Interim Financial Statements include the Financial Statements of the Company and its subsidiary undertakings. They have been prepared using accounting bases and policies consistent with those used in the preparation of the Consolidated Financial Statements of the Company and the Group for the year ended 31 December 2025. These Unaudited Condensed Consolidated Interim Financial Statements do not include all the disclosures required for annual Financial Statements, and accordingly, should be read in conjunction with the Consolidated Financial Statements and other information set out in the Group’s Annual Report for the year ended 31 December 2025.
As a Spanish company operating under EU regulations, the Group also complies with the requirements of Spanish corporate law, including the Commercial Code (Código de Comercio) and the Spanish Capital Companies Act (Ley de Sociedades de Capital), where applicable. These regulations govern the preparation and disclosure of Consolidated Financial Statements.
The definition of Public Interest Entity is set out in Article 2.13 of Directive 2006/43/EC, amended by Article 1 of Directive 2014/56/EU, that states what it is considered to be Public Interest Entities : (a) entities governed by the law of a Member State whose transferable securities are admitted to trading on a regulated market of any Member State; (b) credit institutions as defined in point 1 of Article 3(1) of Directive 2013/36/EU; (c) insurance undertakings within the meaning of Article 2(1) of Directive 91/674/EEC; and (d) entities designated by Member States as public-interest entities. As the company is not included in any of the categories above, it is not considered to be a Public Interest Entity.
- Going concern
These Unaudited Condensed Consolidated Interim Financial Statements have been prepared based on accounting principles applicable to a going concern which assumes that the Group will realise its assets and discharge its liabilities in the normal course of business. Management has carried out an assessment of the going concern assumption and has concluded that the Group can reasonably be expected to generate sufficient cash and cash equivalents to continue operating for the next twelve months.
Management continues to monitor the impact of geopolitical developments. Currently no direct operational impact is expected in the operations of the Group.
2.2 New standards, interpretations and amendments adopted by the Group
The accounting policies adopted in the preparation of the Condensed Consolidated Interim Financial Statements are consistent with those followed in the preparation of the Group’s Annual Consolidated Financial Statements for the year ended 31 December 2025, except for the adoption of new standards effective as of 1 January 2026. The Group has not early adopted any standard, interpretation or amendment that has been issued but is not yet effective.
The following amendments became effective for annual reporting periods beginning on or after 1 January 2026 and have been adopted by the Group in the current period:
- Amendments to IFRS 9 and IFRS 7 – Amendments to the Classification and Measurement of Financial Instruments;
- Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity; and
- Annual Improvements to IFRS Accounting Standards – Volume 11.
The adoption of these amendments has not had a material impact on the Group's Condensed Consolidated Interim Financial Statements.
The IASB has also issued IFRS 18 Presentation and Disclosure in Financial Statements, which replaces IAS 1 and introduces new requirements regarding the presentation and disclosure of information in financial statements, including specified subtotals in the statement of profit or loss, enhanced aggregation and disaggregation principles and disclosures relating to management-defined performance measures. IFRS 18 is effective for annual reporting periods beginning on or after 1 January 2027 and has not been adopted early by the Group.
The Group is currently assessing the impact of IFRS 18. The new standard is expected to affect the presentation and disclosure of information in the Consolidated Financial Statements but is not expected to have a material impact on the Group's financial position, financial performance or cash flows.
2.3 Fair value estimation
The fair values of the Group’s financial assets and liabilities approximate their carrying amounts at the reporting date.
The fair value of financial instruments traded in active markets, such as publicly trading and other financial assets is based on quoted market prices at the reporting date. The quoted market price used for financial assets held by the Group is the current bid price. The appropriate quoted market price for financial liabilities is the current ask price.
The fair value of financial instruments that are not traded in an active market is determined using appropriate valuation techniques. The Group uses valuation methodologies that maximise the use of observable market data where available and minimise the use of unobservable inputs.
Fair value measurements recognised in the Consolidated Statement of Financial Position
The following table provides an analysis of financial instruments measured at fair value after initial recognition, grouped into Levels 1 to 3 according to the observability of the inputs used in determining fair value.
- Level 1 – quoted prices (unadjusted) in active markets for identical assets or liabilities.
- Level 2 – inputs other than quoted prices included within Level 1 that are observable either directly or indirectly.
- Level 3 – valuation techniques using significant inputs that are not based on observable market data.
|
Financial assets or liabilities |
Level 1 |
Level 2 |
Level 3 |
Total |
|
30 Sep 2026 |
|
|
|
|
|
Other financial assets |
|
|
|
|
|
Financial assets at FV through OCI |
10,648 |
- |
1,101 |
11,749 |
|
Financial assets at FV through P&L (*) |
- |
- |
9,725 |
9,725 |
|
Trade and other receivables |
|
|
|
|
|
Receivables (subject to provisional pricing) |
- |
57,191 |
- |
57,191 |
|
Total |
10,648 |
57,191 |
10,826 |
78,665 |
|
|
|
|
|
|
|
31 Dec 2025 |
|
|
|
|
|
Other current financial assets |
|
|
|
|
|
Financial assets at FV through OCI |
62 |
- |
1,101 |
1,163 |
|
Financial assets at FV through P&L (*) |
- |
- |
9,725 |
9,725 |
|
Trade and other receivables |
|
|
|
|
|
Receivables (subject to provisional pricing) |
- |
21,254 |
- |
21,254 |
|
Total |
62 |
21,254 |
10,826 |
32,142 |
(*) The fair value of the Convertible Loan was determined using a valuation model reflecting expected development of Lain Technologies Ltd.
Valuation techniques and significant inputs
The valuation techniques applied by the Group for recurring fair value measurements are summarised below.
|
Financial instrument |
Fair value hierarchy |
Valuation technique |
Significant inputs |
|
Listed equity investments classified as FVOCI |
Level 1 |
Quoted market prices |
Quoted closing market prices |
|
|
|
|
|
|
Receivables subject to provisional pricing |
Level 2 |
Forward pricing model |
Observable LME copper forward prices, forward foreign exchange rates, discount factors and contractual quotational periods |
|
|
|
|
|
|
Unlisted equity investments classified as FVOCI |
Level 3 |
Market approach incorporating company specific information |
Recent transactions, financial position of the investee and other relevant observable and unobservable information |
|
|
|
|
|
|
Convertible Loan to Lain Technologies Ltd |
Level 3 |
Probability-weighted discounted cash flow model |
Expected commercial development of the E-LIX technology, expected timing of commercialisation and discount rates |
Observable market prices are obtained from recognised commodity exchanges and independent pricing sources.
Receivables subject to provisional pricing
The Group sells copper concentrates under contracts containing provisional pricing mechanisms. Revenue is recognised when control of the concentrate is transferred to the customer in accordance with IFRS 15. However, the final consideration remains subject to future movements in the London Metal Exchange ("LME") copper price until the end of the relevant quotational period.
Accordingly, the outstanding receivable contains an embedded derivative within the scope of IFRS 9 and is subsequently remeasured at fair value through profit or loss at each reporting date until final settlement.
The fair value of these receivables is determined using observable forward LME copper prices, forward foreign exchange rates and contractual quotational periods. Consequently, these receivables are classified within Level 2 of the fair value hierarchy.
Level 3 fair value measurements
At 30 September 2026, the Group's recurring Level 3 fair value measurements comprise:
- unlisted equity investments classified as financial assets at fair value through other comprehensive income; and
- the Convertible Loan granted to Lain Technologies Ltd measured at fair value through profit or loss.
The Group measures Level 3 financial instruments using valuation techniques consistent with those applied in the Annual Report for the year ended 31 December 2025. Where available, valuation models maximise the use of observable market inputs. Where observable market data is not available, significant unobservable inputs are used.
The significant unobservable inputs used are summarised below.
|
Significant unobservable input |
Description |
|
|
|
|
Expected commercial development of the E-LIX technology |
Assumptions regarding the expected incremental economic benefits generated by the commercial application of the E-LIX technology
|
|
Forecast operating cash flows |
Financial projections prepared for the valuation of the underlying equity interest
|
|
Discount rate |
Reflects the risks specific to the investment and market participant assumptions |
The fair value of the Convertible Loan is determined using a probability-weighted discounted cash flow model. The valuation incorporates assumptions regarding the expected commercial development of the E-LIX technology, forecast operating cash flows, the expected timing of commercialisation and the discount rate applied. The valuation is reviewed at each reporting date using the most recent information available.
Sensitivity to unobservable inputs
The fair value measurement of the Convertible Loan is sensitive to changes in the significant unobservable inputs used in the valuation. In particular, changes in the expected commercial benefits arising from the application of the E-LIX technology, the forecast operating cash flows of the underlying business and the discount rate applied would result in a different fair value measurement. Higher forecast cash flows or a lower discount rate would generally increase the fair value, whereas lower forecast cash flows or a higher discount rate would reduce the fair value.
There were no transfers between Level 1, Level 2 and Level 3 during the nine-month period ended 30 September 2026.
Convertible Loan granted to Lain Technologies Ltd.
As at 30 September 2026, the carrying amount of the Convertible Loan amounted to €9.7 million, comprising principal and accrued interest.
The Convertible Loan is measured at fair value through profit or loss and is classified within Level 3 of the fair value hierarchy due to the use of significant unobservable inputs.
The loan matured on 31 December 2025. As repayment was not made on maturity, the Group has a contractual right to convert the outstanding principal and accrued interest into a 20% equity interest in Lain Technologies Ltd. At the date of approval of these Unaudited Condensed Consolidated Interim Financial Statements, the Group had neither received repayment nor exercised its contractual conversion right, and discussions with Lain Technologies Ltd. regarding the settlement of the outstanding balance remain ongoing.
The fair value of the Convertible Loan has been determined using a probability-weighted discounted cash flow model that considers the alternative contractual settlement outcomes available under the Convertible Loan Agreement. The valuation incorporates assumptions regarding the expected commercial development of the E-LIX technology, forecast operating cash flows, the expected timing of commercialisation and an appropriate discount rate.
At 30 September 2026, management considered developments since the valuation performed at 31 December 2025, including the technical, operational and commercial performance of the Industrial Plant, and concluded that there had been no material change in the significant valuation assumptions. Accordingly, the fair value of the Convertible Loan remained €9.725 million. No decision has been taken to exercise the conversion right.
2.4 Critical accounting estimates and judgements
The preparation of the Unaudited Condensed Consolidated Interim Financial Statements require management to make judgements, estimates and assumptions that affect the reported amounts of revenues, expenses, assets and liabilities, and the accompanying disclosures, and the disclosure of contingent liabilities at the date of the Consolidated Financial Statements. Estimates and assumptions are continually evaluated and are based on management’s experience and other factors, including expectations of future events that are believed to be reasonable under the circumstances. Uncertainty about these assumptions and estimates could result in outcomes that require a material adjustment to the carrying amount of assets or liabilities affected in future periods.
Provisions are recognised when the Group has a present legal or constructive obligation as a result of past events, it is probable that an outflow of resources will be required to settle the obligation, and a reliable estimate of the amount can be made. If the effect of the time value of money is material, provisions are discounted using a current pre-tax rate that reflects, where appropriate, the risks specific to the liability. Where discounting is used, the increase in the provision due to the passage of time is recognised as a finance cost.
A full analysis of critical accounting estimates and judgements is set out in Note 3.4 of the 2025 audited Financial Statements.
Recoverability of assets related to the E-LIX project
The E-LIX System represents a key area of estimation uncertainty due to the early-stage nature of the project and the significant assumptions involved in assessing the recoverability of capitalised development costs.
Historically, the Group capitalised expenditures related to the construction of the pilot plant and supporting infrastructure, as well as costs associated with feasibility studies and engineering design for a potential industrial-scale application of the E-LIX electrochemical extraction process.
The recoverability of these capitalised amounts is subject to considerable uncertainty and depends on the achievement of several future milestones, including:
- Demonstration of commercial and technical feasibility – The E-LIX Phase 1 plant must validate the E-LIX System’s ability to operate consistently and cost-effectively at scale. Progress to date has highlighted challenges in achieving sustainable throughput levels, and further assessment is pending (see Note 8).
- Market conditions for copper and zinc – Sustained favourable pricing is critical to supporting the project’s economic case.
- Operational and cost performance – The system must achieve targeted recovery rates and cost efficiencies during pilot and potential commercial operation.
- Strength of exclusivity arrangements – The Group retains exclusive rights to deploy the E-LIX System within the Iberian Pyrite Belt, but the value of these rights is contingent on successful commercialisation.
Management assesses the capitalised amounts for indicators of impairment in accordance with IAS 36. Should there be indications of material changes in project assumptions or external conditions, the Group will review the carrying amount of the asset in accordance with IAS 36.
At 31 December 2025, the Group recognised an impairment of €24.1 million in relation to certain assets associated with the E-LIX project. During 2026, the E-LIX plant processed high-zinc, low-copper bulk concentrates to produce saleable copper concentrates and zinc precipitates, with the plant operating stability improved at the throughput levels achieved. Management concluded that the relevant PPE was available for its intended use from 1 January 2026 and commenced depreciation from that date.
However, throughput remained below design capacity and sustained operating and cost performance at scale has not yet been established. Therefore, there is still uncertainty on the recoverability of the related assets and consequently, the impairment remains as at 30 September 2026.
The Group will continue to monitor operational performance and market conditions and will reassess the recoverability of the related assets when new information becomes available.
The valuation of the Convertible Loan also requires management to exercise significant judgement in estimating the expected commercial outcomes of the E-LIX technology, the probability of conversion into equity, the expected timing of commercialisation and the assumptions that a market participant would use in pricing the instrument. Changes in these assumptions could have a material effect on the fair value recognised at the reporting date.
At 30 September 2026, Management considered developments since the valuation performed at 31 December 2025 and concluded that there had been no material change in the significant valuation assumptions. Accordingly, the fair value of the Convertible Loan remained €9.7 million.
- Business and geographical segments
Business segments
The Group has only one distinct business segment, being that of mining operations, which include mineral exploration, development and scrap sales.
Copper concentrates produced by the Group are sold to three off-takers as per the relevant offtake agreements. In addition, the Group has spot agreements for the concentrates not committed to off-takers.
Geographical areas of sales
The Group’s mining activities are located in Spain. The commercialisation of the copper concentrates produced in Spain is carried out through Cyprus. Sales transactions to related parties are on an arm’s length basis in a similar manner to transactions with third parties. Accounting policies used by the Group in different locations are the same as those contained in Note 2.
The table below presents revenues from external customers based on their geographical location, determined by the country of establishment of each customer.
|
Revenue – from external customers |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
|
€'000 |
€'000 |
€'000 |
€'000 |
|
Switzerland |
144,921 |
40,662 |
310,761 |
225,497 |
|
Singapore |
42,726 |
66,013 |
141,265 |
135,669 |
|
Spain |
119 |
78 |
431 |
337 |
|
|
187,766 |
106,753 |
452,457 |
361,503 |
The table below presents revenues from external customers attributed to the country of domicile of the Company.
|
Revenue – from external customers |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
|
€'000 |
€'000 |
€'000 |
€'000 |
|
Cyprus |
13,810 |
7,934 |
34,304 |
26,704 |
|
Spain |
173,956 |
98,819 |
418,153 |
334,799 |
|
|
187,766 |
106,753 |
452,457 |
361,503 |
The geographical location of the specified non-current assets is based on the physical location of the asset in the case of property, plant and equipment and intellectual property and the location of the operation to which they are allocated in the case of goodwill.
|
Non-current assets |
30 Sep 2026 |
31 Dec 2025 |
|
|
€'000 |
€'000 |
|
Spain |
545,507 |
522,648 |
|
|
545,507 |
522,648 |
Revenue represents the sales value of goods supplied to customers; net of value added tax. The following table summarises sales to customers with whom transactions have individually exceeded 10.0% of the Group's revenues.
|
(Euro 000’s) |
|
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
|
Segment |
€’000 |
€’000 |
€’000 |
€’000 |
|
Customer 1 |
Copper |
42,726 |
66,013 |
141,265 |
135,669 |
|
Customer 2 |
Copper |
77,730 |
39,185 |
113,607 |
77,392 |
|
Customer 3 |
Copper |
18,127 |
1,702 |
64,196 |
131,272 |
|
Customer 4 |
Copper |
49,064 |
- |
132,958 |
- |
|
|
|
187,647 |
106,900 |
452,026 |
344,333 |
- Revenue
|
(Euro 000’s) |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Revenue from contracts with customers (1) |
188,752 |
105,064 |
458,849 |
353,608 |
|
Price finalisation adjustments on provisionally priced sales (2) |
4,756 |
(4,981) |
143 |
2,372 |
|
Fair value (losses)/gains relating to provisional pricing within sales (3) |
(5,857) |
6,610 |
(6,954) |
5,204 |
|
Other income (4) |
115 |
60 |
419 |
319 |
|
Total revenue |
187,766 |
106,753 |
452,457 |
361,503 |
All revenue from copper concentrate is recognised at a point in time when the control is transferred. Revenue from freight services is recognised over time as the services are provided.
- Included within Q3 2026 and YTD 2026 is income of €3.6 million (Q3 2025: €2.2 million) and €10.9 million (YTD 2025: €8.2 million), respectively related to the freight services provided by the Group to its customers arising from the sales of copper concentrate under CIF incoterm.
- Represents adjustments to revenue arising from the final settlement of sales contracts that were previously provisionally priced. These amounts result from the reversal of provisions once the final invoice amount has been agreed with the customer.
- Provisional pricing impact represents the change in fair value of the embedded derivative arising on sales of concentrate.
- Other income primarily comprises proceeds from the sale of scrap materials.
- Net Finance Income/(Costs)
|
(Euro 000’s) |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Interest expense |
|
|
|
|
|
Other interest (1) |
(193) |
(546) |
(671) |
(1,487) |
|
Interest on lease liabilities |
(4) |
(9) |
(11) |
(28) |
|
Unwinding of discount on mine rehabilitation provision (Note 19) |
(268) |
(141) |
(791) |
(616) |
|
Interest income |
|
|
|
|
|
Financial interest |
1,152 |
518 |
2,362 |
1,872 |
|
Impairment and losses on disposal of financial instruments |
- |
(2,702) |
- |
(2,702) |
|
Total |
687 |
(2,880) |
889 |
(2,961) |
|
Interest expense capitalised (2) |
90 |
105 |
282 |
429 |
- Interest expenses related to interest accrued on bank payable balances.
- Amounts capitalised within the above table refer to the new crusher and solar plant.
Financial income includes interest received on bank balances of €2.1 million (2025: €0.4 million).
The comparative impairment charge relates to the Pilot Plant loan to Lain, which was fully impaired in 2025 (Note 13).
6. Tax
The Group determines the income tax expense for the period based on the application of relevant tax laws and regulations in each jurisdiction, including current and deferred tax effect. The major components of income tax expense in the Unaudited Condensed Consolidated Interim Statement of Comprehensive Income are:
|
(Euro 000’s) |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Income taxes |
|
|
|
|
|
Current income tax income/(expense) |
(12,226) |
1,909 |
(29,697) |
(13,787) |
|
Deferred tax income/(expense) |
(172) |
(4,990) |
543 |
(4,990) |
|
Income tax expense recognised in the Statement of Comprehensive Income |
(12,398) |
(3,081) |
(29,154) |
(18,777) |
7. Earnings per share
The calculation of the basic and fully diluted profit per share attributable to the ordinary equity holders of the Company is based on the following data:
|
(Euro 000’s) |
Three months ended 30 Sep 2026 |
Three months ended 30 Sep 2025 |
Nine months ended 30 Sep 2026 |
Nine months ended 30 Sep 2025 |
|
Profit attributable to equity holders of the parent |
62,941 |
10,925 |
147,054 |
71,073 |
|
|
|
|
|
|
|
Weighted number of ordinary shares for the purposes of basic earnings per share (000’s) |
153,759 |
140,759 |
152,473 |
140,759 |
|
Basic profit per share (EUR cents/share) |
40.9 |
7.8 |
96.4 |
50.5 |
|
|
|
|
|
|
|
Weighted number of ordinary shares for the purposes of fully diluted earnings per share (000’s) |
160,496 |
147,850 |
159,085 |
146,418 |
|
Fully diluted profit per share (EUR cents/share) |
39.2 |
7.4 |
92.4 |
48.5 |
At 30 September 2026 there are nil warrants, 5,986,334 options and 750,926 share awards (Note 16) (31 December 2025: nil warrants, 6,026,334 options and 443,522 share awards).
8. Property, plant and equipment
|
(Euro 000’s) |
Land and buildings |
Right-of-use assets |
Plant and machinery |
Assets under construction (1) |
Deferred mining costs (3) |
Other assets (4) |
Total |
|
Cost |
|
|
|
|
|
|
|
|
At 1 January 2025 |
86,452 |
6,928 |
340,516 |
100,448 |
73,974 |
980 |
609,298 |
|
Additions |
459 |
- |
- |
37,412 |
21,031 |
- |
58,902 |
|
Reclassifications |
- |
- |
4,907 |
(2,230) |
- |
19 |
2,696 |
|
Increase in rehab. Provision |
116 |
- |
- |
- |
- |
- |
116 |
|
Disposals |
- |
- |
- |
(15) |
- |
- |
(15) |
|
At 30 September 2025 |
87,027 |
6,928 |
345,423 |
135,615 |
95,005 |
999 |
670,997 |
|
Additions |
- |
1,237 |
836 |
10,137 |
1,053 |
- |
13,263 |
|
Changes in rehab. Provision |
(775) |
- |
- |
- |
- |
- |
(775) |
|
Reclassifications |
- |
- |
(2,012) |
9,243 |
- |
- |
7,231 |
|
Disposals |
- |
- |
- |
1 |
- |
(24) |
(23) |
|
At 31 December 2025 |
86,252 |
8,165 |
344,247 |
154,996 |
96,058 |
975 |
690,693 |
|
Additions (2) |
1,881 |
- |
5,902 |
35,555 |
17,022 |
120 |
60,480 |
|
Increase in rehab. Provision |
286 |
- |
- |
- |
- |
- |
286 |
|
Reclassifications (5) |
- |
- |
127,112 |
(126,884) |
- |
- |
228 |
|
30 September 2026 |
88,419 |
8,165 |
477,261 |
63,667 |
113,080 |
1,095 |
751,687 |
|
|
|
|
|
|
|
|
|
|
Depreciation |
|
|
|
|
|
|
|
|
At 1 January 2025 |
30,894 |
2,971 |
140,876 |
- |
24,718 |
807 |
200,266 |
|
Charge for the period |
4,582 |
390 |
24,386 |
- |
6,271 |
43 |
35,672 |
|
At 30 September 2025 |
35,476 |
3,361 |
165,262 |
- |
30,989 |
850 |
235,938 |
|
Charge for the period |
788 |
172 |
3,970 |
- |
2,107 |
9 |
7,046 |
|
Write-off |
- |
- |
- |
- |
- |
(20) |
(20) |
|
At 31 December 2025 |
36,264 |
3,533 |
169,232 |
- |
33,096 |
839 |
242,964 |
|
Charge for the period (6) |
3,370 |
453 |
29,903 |
- |
8,187 |
18 |
41,931 |
|
30 September 2026 |
39,634 |
3,986 |
199,135 |
- |
41,283 |
857 |
284,895 |
|
|
|
|
|
|
|
|
|
|
Net book value |
|
|
|
|
|
|
|
|
30 September 2026 |
48,785 |
4,179 |
278,126 |
63,667 |
71,797 |
238 |
466,792 |
|
At 31 December 2025 |
49,988 |
4,632 |
175,015 |
154,996 |
62,962 |
136 |
447,729 |
(1) Assets under construction at 30 September 2026 were €63.7 million (31 December 2025: €155.0 million) this balance includes €9.4 million for road deviation, €17.4 million for pushback San Dionisio, €7.4 million for sustaining capital, and €17.3 million for tailings dam expenditure.
(2) Additions include as assets under construction, sustaining capital expenditure of €4.5 million (2025: €3.3 million), tailings dams project €6.9 million (2025: €15.8 million), pushback San Dionisio area of €17.4 million, as plant and machinery mainly in the San Dionisio area €5.6 million, acquisition of land and buildings in CSR of €1.9 million and capitalised stripping costs €17.1 million.
(3) Capitalised stripping costs related to Cerro Colorado.
(4) Includes motor vehicles, furniture, fixtures and office equipment which are depreciated over 5-10 years.
(5) Reclassifications included €22.4 million relating to the E-LIX project, €36.7 million relating to the solar plant, €49.3 million relating to the San Dionisio area, €16.6 million relating to the tailings dam expansion and €2.1 million relating to other projects. Reclassifications also included €228 thousand transferred from inventories to property, plant and equipment. Depreciation is recognised on a straight-line basis over the estimated useful lives of the relevant assets, taking into account the remaining life of the mine where appropriate.
(6) During YTD 2026, the Group capitalised 0.3 million of borrowing costs related to the construction of the solar plant phase II and new crusher in accordance with IAS 23. The weighted average interest rate applied to the qualifying borrowings was 1.38% + Euribor. The tax deductibility of these capitalised borrowing costs will be realised over the asset’s useful life through depreciation deductions, rather than as an immediate tax relief.
The above fixed assets are mainly located in Spain.
E-LIX Project
In May 2019, after approximately four years of laboratory work, Atalaya initiated a partnership with Lain Technologies Ltd. for the development of a technology known as E-LIX. The E-LIX technology is an electrochemical extraction process developed by Lain that aims to enable the production of zinc and copper cathodes, as well as other derivatives of these metals, from complex sulphide ores.
In July 2020, Atalaya and Lain executed a Memorandum of Understanding (“MOU”), and have collaborated in the development of the E-LIX technology through several phases, summarised as follows:
- Phase 0: Preliminary work and research.
- Phase 1: Construction and commissioning of the Pilot Plant.
- Phase 2: Operation of the Pilot Plant and feasibility studies.
- Phase 3: Construction and commissioning of an Industrial Scale Plant.
In accordance with the phases stated above, several agreements have been signed, including:
- Construction of the fixed assets required for the use of the E-LIX technology;
- Exclusivity agreements;
- Funding agreements for the construction and the commissioning of the Pilot Plant;
- Funding agreements for the construction and commissioning of the Industrial Plant;
- Operational agreements for the construction of the Industrial Plant; and
- Payment and Credit Compensation Agreement.
The Pilot Plant was constructed during 2021 and confirmed the technical feasibility of E-LIX, demonstrating the ability to selectively leach metals from concentrates and achieve high recovery rates for copper and zinc.
In December 2021, the Company’s Board of Directors approved the construction and financing of a larger-scale demonstration plant with a significantly greater processing capacity than the Pilot Plant (the “Industrial Plant”). From the approval of the construction of the Industrial Plant in 2021, Lain Technologies has been working on constructing and ramping-up the Industrial Plant.
During 2025, Lain intermittently operated the Industrial Plant processing copper concentrates produced by Atalaya and producing a saleable mixed zinc hydroxide product.
While the Industrial Plant has demonstrated the technical functionality of the E-LIX technology at an industrial scale, production volumes have been significantly lower than originally designed resulting in challenging operational and financial results.
As of 30 September 2026, the Industrial Plant has not achieved the level of commercial production envisaged in the feasibility studies. Although the E-LIX technology has been performing broadly in line with the design parameters, certain operational bottlenecks have been identified that limit the plant’s ability to achieve the originally designed production levels without additional capital investments.
At 30 September 2026, the Group’s E-LIX-related PPE and Convertible Loan amounted to €29.6 million, as detailed below:
|
Description |
Caption |
Note |
Amount (€k) |
|
Pilot plant |
Non-current receivables |
13 |
- |
|
Industrial Plant |
Non-current Receivables (prepayments) |
12 |
- |
|
Industrial Plant |
PPE |
8 |
19,895* |
|
Convertible Loan |
Non-current loan |
13 |
9,725 |
|
|
|
|
|
*20k corresponded to capitalised interest
The fair value of the Convertible Loan referred to in Note 13 has been determined independently from the recoverability assessment performed for the E-LIX assets under IAS 36.
Impairment of E-LIX Technology Assets
The E-LIX technology has demonstrated positive results in the recovery of zinc and copper metal, as well as their derivatives, through the treatment of complex sulphide ores. If the E- LIX technology is proven to be financially viable at an industrial scale, the E-LIX technology has the potential to unlock the production of metals from complex ore and its use at an industrial scale could potentially significantly extend the life of mine at Proyecto Riotinto. E-LIX technology is owned by Lain Technologies Ltd.
Atalaya has reviewed both external and internal indicators of impairment in assessing the recoverability of the assets associated with the E-LIX technology (Note 2.4.).
Based on the information currently available, Atalaya has identified Lain’s financial situation as an impairment indicator affecting the recoverability of certain assets, due to the possibility that Lain’s financial constraints may limit the availability of capital investment required to address operational bottlenecks and the ability of the Industrial Plant to achieve throughput volumes sufficient to operate in a financially viable manner; and the risk that Lain may not be able to meet its contractual obligations which could limit Atalaya’s ability to recover outstanding balances.
|
Description |
Nature of the Asset (recoverability) |
Value at 31 December 2025 (€k) |
Impairment 31 December 2025 (€k) |
Net Asset Value at 31 December 2025 (€k) |
Net Asset Value at 30 September 2026 (€k) |
|
Pilot Plant |
Repayments from operational cash flow from the Industrial Plant |
2,726 |
(2,726) |
- |
- |
|
Industrial Plant – Loan |
Repayments depend on the use of the technology and operation in the Industrial Plant |
21,418 |
(21,418) |
- |
- |
|
Industrial Plant - PPE |
Recoverable asset through alternative use in Atalaya’s processing plant (1) |
22,118 |
- |
22,118 |
19,895** |
|
Convertible Loan |
Recoverable by 20% of equity in the E-LIX technology |
9,725 |
- |
9,725 |
9,725 |
(1) Atalaya has carried out an analysis to identify assets that could be used in the existing processing plant other than the E-LIX technology. The opening balance as at 31 December 2025 of €22.118 million includes €0.020 million of capitalised interest.
**The decrease between 31 December 2025 and 30 September 2026 relates to depreciation of €2.223 million due to the reclassification from assets under construction to plant of machinery of €22.4 million related to E-LIX project.
Management reassessed the carrying amounts of the E-LIX-related assets at 30 September 2026 and concluded that no additional impairment or reversal of impairment was required. The fair value of the Convertible Loan also remained unchanged (Note 2.3.)
9. Intangible assets
|
(Euro 000’s) |
Permits (1) |
Licences, R&D and software |
Other intangible assets |
Total |
|
Cost |
|
|
|
|
|
At 1 January 2025 |
78,071 |
1,810 |
27,847 |
107,728 |
|
Additions |
400 |
- |
6,969 |
7,369 |
|
Reclassification |
52 |
28 |
(50) |
30 |
|
At 30 September 2025 |
78,523 |
1,838 |
34,766 |
115,127 |
|
Additions |
- |
10 |
2,104 |
2,114 |
|
Reclassification |
- |
- |
(1) |
(1) |
|
At 31 December 2025 |
78,523 |
1,848 |
36,869 |
117,240 |
|
Additions (2) |
- |
- |
6,866 |
6,866 |
|
30 September 2026 |
78,523 |
1,848 |
43,735 |
124,106 |
|
Amortisation |
|
|
|
|
|
At 1 January 2025 |
35,958 |
1,561 |
- |
37,519 |
|
Charge for the period |
4,084 |
25 |
- |
4,109 |
|
At 30 September 2025 |
40,042 |
1,586 |
- |
41,628 |
|
Charge for the period |
687 |
6 |
- |
693 |
|
At 31 December 2025 |
40,729 |
1,592 |
- |
42,321 |
|
Charge for the period |
3,046 |
24 |
- |
3,070 |
|
At 30 September 2026 |
43,775 |
1,616 |
- |
45,391 |
|
Net book value |
|
|
|
|
|
At 30 September 2026 |
34,748 |
232 |
43,735 |
78,715 |
|
At 31 December 2025 |
37,794 |
256 |
36,869 |
74,919 |
(1) Permits include the mining rights of Proyecto Riotinto, Proyecto Touro, Masa Valverde and Ossa Morena. Additions correspond to the acquisition of new investigation permits.
(2) Additions include capitalised costs relating to Cobre San Rafael (€4.7 million) and Masa Valverde (€2.2 million) according to the policy of the Group.
The ultimate recovery of balances carried forward in relation to areas of interest or all such assets including intangibles is dependent on successful development, and commercial exploitation, or alternatively the sale of the respective areas.
The Group assesses at each reporting date whether there are indicators of impairment and performs impairment testing when such indicators are identified. Intangible assets within the scope of IAS 36 that are not yet available for use are also tested for impairment annually.
The Group’s principal amortised intangible asset relates to the mining rights associated with Proyecto Riotinto. These rights are amortised on a units-of-production basis over the commercially recoverable Ore Reserves of the mine. The last Ore Reserves statement implies a mine life of approximately nine years.
Other intangible assets comprise Proyecto Touro and Proyecto Masa Valverde. These assets are not yet available for their intended use and are therefore not amortised. Amortisation will commence when commercial production begins.
10. Inventories
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
|
Finished products |
4,087 |
3,799 |
|
Materials and supplies |
27,559 |
25,087 |
|
Work in progress |
2,458 |
1,985 |
|
Total inventories |
34,104 |
30,871 |
As of 30 September 2026, copper concentrate produced and not sold amounted to 3,259 tonnes (31 Dec 2025: 4,050 tonnes). Accordingly, the inventory for copper concentrate was €4.1 million (31 Dec 2025: €3.8 million).
Materials and supplies relate mainly to machinery spare parts. Work in progress represents ore stockpiles, which is ore that has been extracted and is available for further processing.
11. Dividends
Cash dividends declared and paid during the period:
|
(Euro 000’s) |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Dividends declared and paid |
8,457 |
3,861 |
18,450 |
3,861 |
Cash dividends declared but not paid during the period:
|
(Euro 000’s) |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Dividends declared but not paid |
- |
6,203 |
- |
6,203 |
Cash dividends paid after the period:
|
(Euro 000’s) |
30 Sep 2026 |
30 Sep 2025 |
31 Dec 2025 |
|
Dividend payable |
8 |
6,203 |
8 |
A final dividend of €0.065 in respect of 2025 was proposed on 18 March 2026 for approval by shareholders at the 2026 Annual General Meeting (“AGM”). The dividend resulted in a total dividend for 2025 of €0.109 per share. The final dividend for 2025 was approved by shareholders at the AGM held on 25 June 2026 and was paid to holders of CREST Depository Interests on 22 July 2026.
On 10 August 2026, the Company's Board of Directors elected to declare a 2026 Interim Dividend of €0.055 per ordinary share, which is equivalent to approximately US$0.064 or £0.047 per share.
12. Trade and other receivables
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
|
Non-current |
|
|
|
Deposits |
4,706 |
902 |
|
Loans |
109 |
109 |
|
Non- current prepayments |
877 |
- |
|
Other non-current receivables |
111 |
111 |
|
|
5,803 |
1,122 |
|
Current |
|
|
|
Trade receivables at fair value – subject to provisional pricing |
40,473 |
5,484 |
|
Trade receivables from Trafigura at fair value – subject to provisional pricing (Note 24.3) |
16,718 |
15,770 |
|
Deposits |
35 |
35 |
|
VAT receivables |
28,013 |
12,739 |
|
Tax advances |
420 |
71 |
|
Prepayments |
5,195 |
4,736 |
|
Other current assets |
1,730 |
2,278 |
|
|
92,584 |
41,113 |
|
Allowance for expected credit losses |
- |
- |
|
Total trade and other receivables |
98,387 |
42,235 |
Trade receivables are shown net of any interest applied to prepayments. Payment terms are aligned with offtake agreements and market standards and generally are 7 days on 90% of the invoice and the remaining 10% at the settlement date which can vary between 1 to 5 months. The fair values of trade and other receivables approximate to their book values.
Non-current deposits included €250k (€250k at 31 December 2025) as a collateral for bank guarantees, which was recorded as restricted cash (or deposit).
Current prepayments include €3.4 million paid to the Huelva Provincial Tax Authority in respect of property tax assessments for the years 2022 to 2025.
13. Loans
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
|||
|
|
|
|
|||
|
Non-current loans |
|
|
|||
|
Loans |
12,451 |
12,451 |
|||
|
Impairment loss on loans |
(2,726) |
(2,726) |
|||
|
|
9,725 |
9,725 |
|||
|
Current loans |
|
|
|||
|
Loans |
- |
20 |
|||
|
|
- |
20 |
|||
Non-current loans comprise the loan granted to Lain Technologies, S.A. in connection with the Pilot Plant and the convertible loan granted to Lain Technologies Ltd. As at 30 September 2026, the carrying amount included principal of €2.3 million and accrued interest of €0.4 million relating to the Pilot Plant loan, together with principal of €9.3 million and accrued interest of €0.4 million relating to the convertible loan.
The Group previously recognised a full impairment of the Pilot Plant loan, as recovery of the outstanding balance was not considered probable. The loan bore interest at EURIBOR 12M plus 2% per annum.
On 30 September 2024 the Group signed a convertible loan agreement, granting a credit facility of up to €10 million with a fixed term until 31 December 2025. As at 31 December 2025, the loan was classified as non-current. This balance bears interest at EURIBOR 3M + 2% per annum.
As the Convertible Loan was not repaid on maturity, the Group has the contractual right to convert the outstanding principal and accrued interest into a 20% equity interest in Lain Technologies Ltd. At the date of approval of these interim financial statements, the Group had neither received repayment nor exercised its conversion right. The Convertible Loan matured on 31 December 2025. No further contractual interest has accrued since maturity, as the loan terms do not provide for the accrual of interest after the contractual maturity date.
14. Other financial assets
The Group's other financial assets comprise strategic equity investments and other financial assets held outside the ordinary course of trading activities. Equity investments are measured in accordance with IFRS 9 and are classified either as financial assets at fair value through other comprehensive income or at fair value through profit or loss, depending on the nature and purpose of the investment.
The movement in other financial assets during the period was as follows:
|
(Euro 000’s) |
Non-current |
Current |
Total |
|
At 31 December 2025 |
1,101 |
62 |
1,163 |
|
Acquisition of equity investment |
8,453 |
- |
8,453 |
|
Fair value gain/(loss) recognised in OCI |
2,164 |
(31) |
2,133 |
|
30 September 2026 |
11,718 |
31 |
11,749 |
The movement recognised in Other Comprehensive Income in respect of financial assets designated at FVOCI during the period was as follows:
|
(Euro 000’s) |
Nine month period ended 30 Sep 2026 |
|
Gross fair value gain recognised in OCI |
2,133 |
|
Deferred tax recognised in OCI |
(540) |
|
Net gain recognised in OCI |
1,593 |
On 2 April 2026, the Group completed the acquisition of 4,500,000 common shares of Lara Exploration Ltd. ("Lara") through participation in a private placement announced by Lara.
Lara is a Canadian mineral exploration company listed on the TSX Venture Exchange, focused on the acquisition, exploration and development of mineral projects in South America. The company currently has a portfolio of exploration assets located principally in Brazil, Peru and Chile and operates through a prospect generation business model, whereby exploration projects are advanced either directly or through strategic joint venture partnerships.
The Group invested C$13.5 million in the private placement, subscribing for shares at C$3.00 per share. Following completion of the transaction, the Group held approximately 7.3% of Lara's issued and outstanding share capital.
Management concluded that the investment does not provide the Group with control, joint control or significant influence over Lara. Accordingly, the investment is accounted for as an equity instrument within the scope of IFRS 9 Financial Instruments and has been designated, upon initial recognition, at fair value through other comprehensive income ("FVOCI"), consistent with the Group's investment strategy for strategic equity holdings.
At 30 September 2026, the investment was measured using the quoted market price of Lara's shares on the TSX Venture Exchange. The resulting increase in fair value during the period was recognised within Other Comprehensive Income and included within the FVOCI reserve in equity.
As at 30 September 2026, the Group's principal equity investments comprised:
|
Company |
Country |
Activity |
Classification |
|
Lara Exploration Ltd. |
Canada |
Mineral exploration |
FVOCI |
|
Explotaciones Gallegas del Cobre, S.L. |
Spain |
Mineral exploration |
FVOCI |
|
KEFI Gold and Copper plc |
United Kingdom |
Mineral exploration |
FVOCI
|
|
Prospech Limited |
Australia |
Mineral exploration |
FVOCI |
Further information regarding the fair value measurement hierarchy of the Group's financial assets is provided in Note 2.3.
15. Cash and cash equivalents
|
(Euro 000’s) |
30 Sep 2026 |
30 Jun 2026 |
31 Dec 2025 |
30 Sep 2025 |
30 Jun 2025 |
|
Unrestricted cash and cash equivalents at Group level |
331,256 |
293,987 |
146,505 |
79,380 |
83,747 |
|
Unrestricted cash and cash equivalents at Operation level |
22,819 |
56,295 |
19,801 |
34,430 |
19,266 |
|
Consolidated cash and cash equivalents |
354,075 |
350,282 |
166,306 |
113,810 |
103,013 |
The table above provides a comprehensive overview of the cash and cash equivalents held by Atalaya as of 30 September 2026.
Cash and cash equivalents denominated in the following currencies:
|
(Euro 000’s) |
30 Sep 2026 |
30 June 2026 |
31 Dec 2025 |
30 Sep 2025 |
30 June 2025 |
|
Euro – functional and presentation currency |
262,489 |
242,360 |
104,902 |
50,840 |
55,821 |
|
Great Britain Pound |
967 |
1,099 |
142 |
568 |
60 |
|
United States Dollar |
90,619 |
106,823 |
61,262 |
62,402 |
47,132 |
|
Consolidated cash and cash equivalents |
354,075 |
350,282 |
166,306 |
113,810 |
103,013 |
16. Share capital and share premium
|
Issued and fully paid |
|
|
Shares |
Share Capital |
Share premium |
Total |
|
Issue Date |
Price (£) |
Details |
000’s |
€'000 |
€'000 |
€'000 |
|
31 December 2025/1 January 2026 |
|
140,759 |
12,668 |
321,856 |
334,524 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
31-Dec-25 |
|
|
140,759 |
12,668 |
321,856 |
334,524 |
|
28-Jan-26 |
10.00 |
Issue of new shares |
13,000 |
1,170 |
143,779 |
144,949 |
|
At 30-Sep-26 |
|
|
153,759 |
13,838 |
465,635 |
479,473 |
Issued capital
- On 28 January 2026, following the initial announcement on 27 January 2026, the Company completed an equity offering, raising total gross proceeds of £130 million (approximately €150 million).
The transaction resulted in the issuance of 13,000,000 new ordinary shares at a placing price of £10.00 per share, which were allocated as follows: 12,730,000 new ordinary shares placed with new institutional investors and existing shareholders, and 270,000 new ordinary shares subscribed by eligible retail investors via RetailBook (including 4,000 shares subscribed by Non-Executive Director Mike Armitage).
Share issuance costs of €5.3 million were deducted from share premium, resulting in net proceeds of €144.9 million. Of this amount, €1.2 million was recognised as share capital and €143.8 million as share premium, as reflected in the table above.
The 13,000,000 newly issued shares represent approximately 9.2% of the Company’s total issued ordinary share capital outstanding prior to the Fundraise.
The Company's share capital at 30 September 2026 is 153,759,043 ordinary shares of €0.09 each.
Share Options
Details of share options outstanding as at 30 September 2026:
|
Grant date |
Expiry date |
Exercise price £ |
Share options |
||||
|
30 Jun 2020 |
29 Jun 2030 |
1.475 |
410,000 |
||||
|
24 Jun 2021 |
23 Jun 2031 |
3.090 |
838,000 |
||||
|
22 Jun 2022 |
30 Jun 2027 |
3.575 |
890,000 |
||||
|
22 May 2023 |
21 May 2028 |
3.270 |
1,020,000 |
||||
|
11 Jun 2024 |
10 Jun 2029 |
4.135 |
1,078,334 |
||||
|
22 Dec 2024 |
21 Dec 2029 |
3.335 |
150,000 |
||||
|
9 Jul 2025 |
9 Jul 2030 |
4.603 |
1,600,000 |
||||
|
Total |
5,986,334 |
||||||
|
|
|
||||||
|
|
|
Weighted average exercise price £ |
Share options |
||||
|
At 1 January 2026 |
3.676 |
6,026,334 |
|||||
|
Options executed during the period |
4.440 |
(40,000) |
|||||
|
30 September 2026 |
3.681 |
5,986,334 |
|||||
Warrants
As at 30 September 2026 and 2025 there were no warrants.
Conditional share awards
As agreed on 23 April 2025, the Company granted conditional share awards under the Atalaya LTIP 2020 to Directors and PDMRs. These awards are subject to the achievement of performance conditions over a three-year period and their continuing employment at that time, after which the shares are granted. However, they remain subject to a two-year holding period, meaning the beneficiary may not fully realise or dispose of the shares until the end of year five.
The conditional share awards granted are summarised below:
|
Name |
Role |
Maximum number of shares awarded |
Grant date |
Vesting schedule |
|
Alberto Lavandeira |
Chief Executive Officer |
218,000 |
23/04/2025 |
Vesting of 3 years, subject to performance |
|
César Sánchez |
Chief Financial Officer (PDMR) |
113,091 |
23/04/2025 |
Same as above |
|
Enrique Delgado |
Corporate Institutional Adviser (Former GM Riotinto) |
112,431 |
23/04/2025 |
Same as above |
|
|
|
443,522 |
|
|
No consideration was paid for the grant of these awards. Vesting is conditional on performance criteria and continued employment. The awards are subject to malus and clawback provisions.
Conditional share awards granted in 2026
On 24 April 2026, the Company granted conditional share awards under the 2020 LTIP over a maximum of 307,404 ordinary shares. The awards comprise 100,513 shares to the Chief Executive Officer, 54,750 shares to the Chief Financial Officer and 152,141 shares to other employees.
Awards granted to the Chief Executive Officer and the Chief Financial Officer are subject to the achievement of applicable performance conditions over a three-year performance period and continued employment. Following vesting, any shares delivered are subject to a two-year holding period and customary malus and clawback provisions.
For employees who are not PDMRs, the terms provide for the allocation of one third of the maximum award immediately following the 2026 Annual General Meeting. Two further allocations of up to one third each are subject to the applicable company and individual performance underpin on the first and second anniversaries of grant.
No consideration was paid for the grant of the awards.
|
Name |
Role |
Maximum number of shares awarded |
|
Alberto Lavandeira |
Chief Executive Officer |
100,513 |
|
César Sánchez |
Chief Financial Officer |
54,750 |
|
Other employees |
Employees |
152,141 |
|
|
|
307,404 |
17. Other reserves
|
(Euro 000’s) |
Share-based benefit |
Bonus share |
Depletion factor (1) |
FV reserve of financial assets at FVOCI (2) |
Non-Distributable reserve (3) |
Distributable reserve (4) |
Total |
|
|
At 1 January 2025 |
12,869 |
208 |
46,727 |
(1,163) |
8,458 |
21,675 |
88,774 |
|
|
Recognition of share- based payments |
1,657 |
- |
- |
- |
- |
- |
1,657 |
|
|
Recognition of non-distributable reserve |
- |
- |
- |
- |
685 |
- |
685 |
|
|
Recognition of distributable reserve |
- |
- |
- |
- |
- |
(670) |
(670) |
|
|
Change in fair value of financial assets at fair value through OCI |
- |
- |
- |
29 |
- |
- |
29 |
|
|
Other changes in reserves |
(134) |
- |
- |
- |
- |
- |
(134) |
|
|
At 30 September 2025 |
14,392 |
208 |
46,727 |
(1,134) |
9,143 |
21,005 |
90,341 |
|
|
Recognition of distributable reserve |
- |
- |
- |
- |
(684) |
683 |
(1) |
|
|
Recognition of share-based payments |
(1,229) |
- |
- |
- |
- |
- |
(1,229) |
|
|
Change in fair value of financial assets at fair value through OCI |
- |
- |
- |
10 |
- |
- |
10 |
|
|
Other changes in reserves |
134 |
- |
- |
- |
- |
- |
134 |
|
|
At 31 December 2025 |
13,297 |
208 |
46,727 |
(1,124) |
8,459 |
21,688 |
89,255 |
|
|
Recognition of share-based payments |
2,479 |
- |
- |
- |
- |
- |
2,479 |
|
|
Recognition of non-distributable reserve |
- |
- |
- |
- |
6,861 |
- |
6,861 |
|
|
Recognition of distributable reserve |
- |
- |
- |
- |
- |
19,583 |
19,583 |
|
|
Recognition of depletion factor |
- |
- |
21,271 |
- |
- |
- |
21,271 |
|
|
Change in fair value of financial assets at fair value through OCI |
- |
- |
- |
1,593 |
- |
- |
1,593 |
|
|
Other changes in reserves |
- |
- |
- |
- |
321 |
- |
321 |
|
|
30 September 2026 |
15,776 |
208 |
67,998 |
469 |
15,641 |
41,271 |
141,363 |
|
|
|
|
|
|
|
|
|
|
|
- Depletion factor reserve
At 30 September 2026, the Group has recognised €70.0 million (30 September 2025: €46.7 million) as a depletion factor reserve as per the Spanish Corporate Tax Act.
- Fair value reserve of financial assets at FVOCI
The Group has elected to recognise changes in the fair value of certain investments in equity securities in OCI. These changes are accumulated within the FVOCI reserve within equity. The Group transfers amounts from this reserve to retained earnings when the relevant equity securities are derecognised.
- Non-distributable reserve
To comply with Spanish Law, the Group needed to record a reserve of profits generated equal to a 10% of profit/(loss) for the year until 20% of share capital is reached.
- Distributable reserve
Includes the transfer from income for the year attributable to the parent for 2025.
18. Trade and other payables
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
|
Non-current |
|
|
|
Other non-current payables |
12,506 |
12,506 |
|
Share based payment non-financial liability |
816 |
225 |
|
Government grant |
1,434 |
1,411 |
|
|
14,756 |
14,142 |
|
Current |
|
|
|
Trade payables |
98,622 |
87,938 |
|
Trade payables to Impala Terminals (Note 24.3) |
371 |
155 |
|
Share based payment non-financial liability |
10,271 |
6,565 |
|
Accruals |
1,994 |
1,873 |
|
Other current payables |
11,782 |
9,586 |
|
|
123,040 |
106,117 |
As of 30 September 2026, other non-current payables included €9.6 million related to liabilities arising from the potential acquisition of 80% of the shares of Cobre San Rafael, SL, in accordance with the Shareholders’ Agreement (note 9). An additional €2.8 million related to the acquisition of Atalaya Masa Valverde SL (formerly Cambridge Minería España, SL) and Atalaya Ossa Morena SLU (formerly Rio Narcea Nickel, SL) (note 1).
Other current payables include €6.8 million, also associated with the potential increase in the stake of Cobre San Rafael, S.L., under the Shareholders' Agreement (note 9). This amount is classified as current, as the likelihood of reaching the associated milestone is considered high, making settlement probable within twelve months of the reporting date. Other current payables also include €3.6 million of withholding taxes payable to the tax authorities.
Trade payables primarily relate to the acquisition of materials, supplies and other services. These payables are non-interest bearing and are not secured by any guarantees. The fair value of trade and other payables approximates their carrying values.
Trade payables are non-interest-bearing and are normally settled on 60-day terms.
Share-based payment liabilities
At 30 September 2026, the Group recognised share-based payment liabilities totalling €11.1 million in respect of cash-settled share-based payment arrangements.
These liabilities comprise:
- €3.5 million relating to the 2025 Deferred Cash Incentive Plan, under which participants receive units that are economically linked to the Company's share price and that are settled exclusively in cash; and
- €7.6 million relating to share options granted to non C-Suite employees under the LTIP 2020 that are accounted for as cash-settled share-based payments.
The liabilities represent the fair value of the outstanding awards at the reporting date and are remeasured at each reporting date until settlement, with changes in fair value recognised in profit or loss in accordance with IFRS 2.
2025 Deferred Cash Incentive Plan
The 2025 Deferred Cash Incentive Plan was formally approved on 9 March 2026 with an effective date of 9 July 2025. The plan replaced the annual share option grants historically awarded to non C-Suite employees under the LTIP 2020 up to and including 2024.
Under the plan, participants receive units that are economically linked to the Company's share price but are settled exclusively in cash. Each unit represents a conditional right to receive a cash payment equal to the excess of the market price of a share over the exercise price.
The exercise price was set at £4.6035 per share, corresponding to the average of the mid-market closing price of the Company's shares over the five dealing days preceding 9 July 2025.
The units vest in three tranches: one third vested on the grant date, one third will vest on 9 July 2026 and the remaining one third will vest on 9 July 2027, subject to continued employment. Vested units may be exercised until 9 July 2030.
At 30 September 2026, the liability recognised in respect of the 2025 Deferred Cash Incentive Plan amounted to €3.5 million (31 December 2025: €1.6 million).
Cash-settled LTIP 2020 options granted to non C-Suite employees
Following the amendment approved by the Board in May 2025, the Company may, at its discretion, settle certain LTIP 2020 option exercises granted to non C-Suite employees in cash instead of issuing shares. Based on the Group's settlement practice and management's assessment, these awards are accounted for as cash-settled share-based payments in accordance with IFRS 2.
At 30 September 2026, the liability recognised in respect of these awards amounted to €7.6 million (31 December 2025: €5.2 million). The liability is measured at fair value at each reporting date until settlement, with changes in fair value recognised in profit or loss.
19. Provisions
|
(Euro 000’s) |
Other provisions |
Legal costs |
Rehabilitation costs |
Total costs |
||
|
At 1 January 2025 |
- |
395 |
29,849 |
30,244 |
||
|
Additions |
- |
- |
- |
- |
||
|
Use of provision |
- |
(150) |
(434) |
(584) |
||
|
Increase in provision |
- |
- |
116 |
116 |
||
|
Finance cost |
- |
- |
616 |
616 |
||
|
At 30 September 2025 |
- |
245 |
30,147 |
30,392 |
||
|
Additions |
1,197 |
- |
- |
1,197 |
||
|
Revision of estimates |
- |
- |
(775) |
(775) |
||
|
Use of provision |
- |
- |
(385) |
(385) |
||
|
Finance cost |
- |
- |
180 |
180 |
||
|
At 31 December 2025 |
1,197 |
245 |
29,167 |
30,609 |
||
|
Additions |
371 |
- |
- |
371 |
||
|
Use of provision |
- |
(15) |
(108) |
(123) |
||
|
Increase in provision |
- |
- |
286 |
286 |
||
|
Finance cost |
- |
- |
791 |
791 |
||
|
30 September 2026 |
1,568 |
230 |
30,136 |
31,934 |
||
|
|
|
|
|
|
||
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
||||
|
Non-current |
29,813 |
28,764 |
||||
|
Current |
2,121 |
1,845 |
||||
|
Total |
31,934 |
30,609 |
||||
Rehabilitation provision
Rehabilitation provision represents the accrued cost required to provide adequate restoration and rehabilitation upon the completion of production activities. These amounts will be settled when rehabilitation is undertaken, generally over the project’s life.
The discount rate used in the calculation of the net present value of the liability as at 30 September 2026 was 3.67% (31 December 2025: 3.67%), which is the 15-year Spanish Government Bond rate for 2026. An inflation rate of 2%-2.30% (31 December 2025: 2%-2.90%) is applied on annual basis.
Legal provision
As at 30 September 2026, the Group has been named as a defendant in several legal proceedings in Spain, the outcomes of which remain uncertain. Management individually reviewed each case and made a provision of €230k as of 30 September 2026 for these claims.
Other provisions
During 2025, the Huelva Cadastral Office notified Atalaya Riotinto Minera, S.L.U., a subsidiary of the Group, of a revision of the cadastral value of certain properties from €5.2 million to €90.1 million, effective from 30 December 2021. The Group challenged this revision and an economic- administrative appeal was filed before the Regional Economic- Administrative Court of Andalusia, which remains pending resolution as of 30 September 2026.
Following the revision, additional property tax assessments relating to the years 2022 to 2025 amounting to €3.4 million were issued by the Huelva Provincial Tax Authority. These assessments were paid in January 2026 in order to avoid late payment interest while the Group continues to challenge the underlying cadastral valuation.
The maximum potential exposure associated with this matter is estimated at approximately €4.4 million as of 31 December 2025. Based on the assessment performed by management and its external advisors, the Group recognised a provision of €1.6 million, included within “Other provisions”, representing management’s best estimate of the probable obligation at the reporting date. The final outcome of this matter remains uncertain and may differ materially from the estimate recorded.
20. Borrowings
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
|
Non-current borrowings |
|
|
|
Credit facilities |
6,316 |
5,708 |
|
|
6,316 |
5,708 |
|
Current borrowings |
|
|
|
Credit facilities |
5,620 |
38,638 |
|
|
5,620 |
38,638 |
The Group had credit approval for unsecured facilities totalling €93.0 million (€97.2 million at 31 December 2025). During 2026, Atalaya drew down some of its existing credit facilities to finance the solar plant, payable amount of €5.9 million at 30 September 2026 (€9.0 million at 31 December 2025) and for the construction of a new part of the processing plant payable amount of €1.1 million at 30 September 2026 (€1.9 million at 31 December 2025).
Margins on borrowing with variable interest rates, usually 3 months EURIBOR and 12 months EURIBOR, range from 1.10% to 1.93% with an average margin of 1.25%.
At 30 September 2026, the Group had used €11.9 million of its facilities and had undrawn facilities of €81.1 million.
Net cash reconciliation
Reconciliation of Liabilities Arising from Financing Activities
The reconciliation below provides information on changes in liabilities arising from financing activities, including both cash and non-cash changes.
|
Net cash (€'000) |
30 Sep 2026 |
31 Dec 2025 |
|
|
|
|
|
Cash and cash equivalents |
354,075 |
166,306 |
|
Borrowings – repayable within one year |
(5,620) |
(38,638) |
|
Borrowings – repayable after one year |
(6,316) |
(5,708) |
|
Lease – as per IAS 7 |
(3,994) |
(4,473) |
|
Net cash excluding lease liabilities |
342,139 |
121,960 |
|
Net cash including lease liabilities |
338,145 |
117,487 |
|
€'000 |
Cash |
Borrowings |
Lease |
Total |
|
Net cash as at 1 Jan 2025 |
52,878 |
(17,787) |
(3,801) |
31,290 |
|
Financing cash flows |
62,267 |
- |
- |
62,267 |
|
Proceeds from borrowings |
- |
(25,069) |
- |
(25,069) |
|
Repayment of borrowings |
- |
18,794 |
389 |
19,183 |
|
Foreign exchanges adjustments |
(1,335) |
- |
- |
(1,335) |
|
Other changes |
|
|
|
|
|
Interest paid |
- |
1,487 |
28 |
1,515 |
|
Interest expense |
- |
(1,487) |
(28) |
(1,515) |
|
Other changes |
- |
- |
(29) |
(29) |
|
Net cash as at 30 Sep 2025 |
113,810 |
(24,062) |
(3,441) |
86,307 |
|
Financing cash flows |
58,590 |
- |
- |
58,590 |
|
Proceeds from borrowings |
- |
(12,847) |
- |
(12,847) |
|
Repayment of borrowings |
- |
(7,437) |
176 |
(7,261) |
|
Foreign exchanges adjustments |
(6,094) |
- |
- |
(6,094) |
|
Other changes |
|
|
|
|
|
Interest paid |
- |
(249) |
(7) |
(256) |
|
Interest expense |
- |
249 |
7 |
256 |
|
Other changes |
- |
- |
(1,208) |
(1,208) |
|
Net cash as at 31 December 2025 |
166,306 |
(44,346) |
(4,473) |
117,487 |
|
Financing cash flows |
189,193 |
- |
- |
189,193 |
|
Proceeds from borrowings |
- |
(18,483) |
- |
(18,483) |
|
Repayment of borrowings |
- |
50,894 |
479 |
51,373 |
|
Foreign exchanges adjustments |
(1,424) |
- |
- |
(1,424) |
|
Other changes |
|
|
|
|
|
Interest paid |
- |
- |
11 |
11 |
|
Interest expense |
- |
- |
(11) |
(11) |
|
Net cash as at 30 Sep 2026 |
354,075 |
(11,936) |
(3,994) |
338,145 |
21. Lease liabilities
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
|
Non-current |
|
|
|
Lease liabilities |
3,362 |
3,834 |
|
|
3,362 |
3,834 |
|
Current |
|
|
|
Lease liabilities |
632 |
639 |
|
|
632 |
639 |
Lease liabilities
The Group entered into lease arrangements for the renting of land and a warehouse which are subject to the adoption of all requirements of IFRS 16 Leases (Note 2.2). The Group has elected not to recognise right-of-use assets and lease liabilities for short-term leases that have a lease term of 12 months or less and leases of low-value assets.
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
|
Present value of minimum lease payments due |
|
|
|
- Within one year |
632 |
639 |
|
- Two to five years |
2,436 |
2,464 |
|
- Over five years |
926 |
1,370 |
|
|
3,994 |
4,473 |
|
|
|
|
|
(Euro 000’s) |
30 Sep 2026 |
30 Sep 2025 |
|
Lease liabilities |
|
|
|
At 1 January |
4,473 |
3,801 |
|
Interest expense |
11 |
29 |
|
Lease payments |
(490) |
(389) |
|
At 30 Sep |
3,994 |
3,441 |
|
|
|
|
|
At 30 Sep |
|
|
|
Non-current liabilities |
3,362 |
2,965 |
|
Current liabilities |
632 |
476 |
|
|
3,994 |
3,441 |
22. Acquisition, incorporation and disposal of subsidiaries
There were no acquisitions or incorporation of subsidiaries during the nine-month period ended 30 September 2026 and 2025.
23. Winding-up of subsidiaries
There were no operations wound up during the nine-month period ended 30 September 2026 and 2025.
24. Related party transactions
The following transactions were carried out with related parties:
24.1 Compensation of key management personnel
The total remuneration and fees of Directors (including Executive Directors) and other key management personnel was as follows:
|
(Euro 000’s) |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Directors’ remuneration and fees |
457 |
217 |
1,089 |
846 |
|
Director’s bonus (1) |
- |
- |
407 |
294 |
|
Share option-based benefits and other benefits to directors |
110 |
598 |
589 |
724 |
|
Share award benefits to Directors |
113 |
58 |
268 |
102 |
|
Key management personnel fees |
223 |
220 |
648 |
661 |
|
Key management bonus (1) |
120 |
- |
359 |
325 |
|
Share option-based and other benefits to key management personnel |
393 |
421 |
766 |
551 |
|
Share award benefits to key management |
61 |
30 |
142 |
85 |
|
|
1,477 |
1,544 |
4,268 |
3,588 |
- These amounts related to the performance bonus for 2025 and 2024 approved by the Board of Directors of the Company during 2026 and 2025. Director’s bonus relates to the amount approved for the CEO as an executive director and key management bonus relates to the amount approved for other key management personnel which are not directors of Atalaya Mining Copper, S.A.
Effective 1 January 2025, the Group included the General Manager of Proyecto Touro as a member of its key management personnel. The decision reflected the formal creation of the role and its strategic relevance, as the position entails direct responsibility over the planning, direction and control of all operational and development activities at Proyecto Touro.
On 24 July 2025, Fernando Araúz de Robles Villalón was appointed General Manager of Proyecto Riotinto, succeeding Enrique Delgado, thereby becoming a member of key management from that date.
24.2 Share-based benefits
No share options were granted to the directors or key management personnel during the nine-month period ended 30 September 2026 (YTD 2025: 1,600,000 share options).
24.3 Transactions with related parties
Trafigura ceased to be a shareholder of the Company on 12 August 2026. From that date, Jesús Fernández ceased to represent Trafigura on the Board and continued as a director in his personal capacity. In the absence of any other basis for a related party relationship, Trafigura ceased to be a related party under IAS 24 on that date.
However, Trafigura remains a related party for the purposes of UKLR 8.1.11R until 4 February 2027, being 12 months after its shareholding fell below the 20% substantial shareholder threshold. Any disclosures below covering transactions after 12 August 2026 or balances at 30 September 2026 are provided as additional information on that basis.
i) Transaction with Trafigura and Impala Terminals
|
(Euro 000’s) |
Three month period ended 30 Sep 2026 |
Three month period ended 30 Sep 2025 |
Nine month period ended 30 Sep 2026 |
Nine month period ended 30 Sep 2025 |
|
Trafigura Pte Ltd– Revenue from contracts (a) |
41,179 |
66,797 |
140,641 |
133,707 |
|
Gain / (losses) relating provisional pricing within sales |
1,547 |
(782) |
624 |
1,964 |
|
|
42,726 |
66,015 |
141,265 |
135,671 |
|
Impala Terminals Huelva S.L.U. - Port Handling and Warehousing services (b) |
(546) |
(758) |
(1,866) |
(1,886) |
|
Trafigura – Net revenue from contracts |
42,180 |
65,257 |
139,399 |
133,785 |
(a) Offtake agreement and spot sales to Trafigura
Offtake agreement
In May 2015, the Company agreed terms with key stakeholders in a capitalisation exercise to finance the re-start of Proyecto Riotinto (the "2015 Capitalisation").
As part of the 2015 Capitalisation, the Company entered into offtake agreements with some of its large shareholders, one of which was Trafigura Pte Ltd ("Trafigura"), under which the total forecast concentrate production from Proyecto Riotinto was committed ("2015 Offtake Agreements").
During Q3 2026, the Company completed 2 sales transactions under the terms of the 2015 Offtake Agreements valued at €20.1 million (Q3 2025: 1 sale valued at €8.5 million). In addition, in Q3 2026, a pricing adjustment of €0.5 million was recorded. These amounts represent the total value of the offtake sales completed during the period and therefore do not reconcile directly to the revenue recognised in the table above.
Spot Sales Agreements
Due to various expansions implemented at Proyecto Riotinto in recent years, volumes of copper concentrate and zinc precipitate have been periodically available for sale outside of the Company's various Offtake Agreements.
In Q3 2026, the Company completed 2 spot sales (Q3 2025: 4 spot sales valued at €56.8 million) valued at €23.0 million. In addition, in Q3 2026, a pricing adjustment of negative €2.4 million was recorded. These amounts represent the total value of the spot sales completed during the period and therefore do not reconcile directly to the revenue recognised in the table above.
Sales transactions with related parties are conducted on an arm’s length basis, consistent with transactions with independent third parties.
(b) Port Handling and Warehousing services
The Group has in place a port handling, storage and shipping services agreement with Impala Terminals Huelva, S.L.U. (“Impala Terminals”) in respect of copper concentrates produced from Proyecto Riotinto.
The agreement covers export concentrate volumes that are not committed under the Group’s offtake arrangements, as well as volumes committed to the Trafigura Group under its offtake arrangement. The agreement remains in force at 30 September 2026.
Impala Terminals was historically treated as a related party through its relationship with Trafigura.
Transactions with Impala Terminals are conducted under normal commercial terms and on an arm’s length basis, consistent with arrangements that would be entered into with independent third parties.
ii) Period-end balances with Trafigura and Impala Terminals
|
(Euro 000’s) |
30 Sep 2026 |
31 Dec 2025 |
|
Receivable from Trafigura (Note 12) |
|
|
|
Trafigura – Debtor balance- subject to provisional pricing |
16,718 |
15,770 |
|
|
16,718 |
15,770 |
|
|
|
|
|
Payable to Impala Terminals (Note 18) |
|
|
|
Impala Terminals - Payable balance |
(371) |
(155) |
|
|
(371) |
(155) |
The receivable from Trafigura relates to provisionally priced concentrate sales and is settled in accordance with the relevant sales agreements. The payable to Impala Terminals relates to port handling, storage and shipping services and is settled in accordance with the terms of the service agreement. Both balances are non-interest-bearing.
25. Contingent liabilities
Judicial and administrative cases
In the normal course of business, the Group may be involved in legal proceedings, claims and assessments. Such matters are subject to many uncertainties, and outcomes are not predictable with assurance. Legal fees for such matters are expensed as incurred and the Group accrues for adverse outcomes as they become probable and estimable.
26. Commitments
There are no minimum exploration requirements at Proyecto Riotinto. However, the Group is required to pay applicable local property taxes and maintain the Riotinto site in compliance with all applicable regulatory requirements.
In 2012, Atalaya Riotinto Minera, S.L.U. entered into a 50/50 joint venture with Rumbo 5. Cero, S.L. ("Rumbo") to evaluate and exploit the potential of the class B resources in the tailings dam and waste areas at Proyecto Riotinto (mainly residual gold and silver in the old gossan tailings). Under the joint venture agreement, ARM will be the operator of the joint venture, will reimburse Rumbo for the costs associated with the application for classification of the Class B resources and will fund the initial expenditure of a feasibility study up to a maximum of €2.0 million. Costs are then borne by the joint venture partners in accordance with their respective ownership interests.
27. Significant events
The following significant corporate events occurred during the nine-month period ended 30 September 2026:
Changes in major shareholdings
- On 5 January 2026, Cobas Asset Management, S.G.I.I.C., S.A. notified the Company that its voting rights had decreased from 14.47% to 9.89%.
- On 4 February 2026, Urion Holdings (Malta) Limited, a member of the Trafigura Group and the Company's largest shareholder, announced the sale of 14,000,000 ordinary shares through an accelerated bookbuild. Following completion of the transaction, Urion Holdings (Malta) Limited remained the Company's largest shareholder, holding 10.94% of the Company's issued share capital.
- On 10 April 2026, Cobas Asset Management, S.G.I.I.C., S.A. notified the Company that its voting rights had further decreased to 4.60%.
- On 16 April 2026, the Company announced a major shareholding notification reporting a holding of 3.20% of the Company's voting rights through Rovida Worldwide Investments Limited.
- On 12 August 2026, Urion Investment Holdings Limited (“Trafigura” or the “Seller”), a member of the Trafigura Group, announced that it had agreed to sell 16,821,212 ordinary shares at the price of 915 pence per share, raising aggregate gross proceeds of approximately £154 million. Following settlement of the transaction, Trafigura ceased to hold any shares in the Company. The Company received no proceeds from the sale.
Equity offering
- On 28 January 2026, the Company completed an equity offering through an institutional placing and retail offer, issuing 13,000,000 new ordinary shares at a price of £10.00 per share and raising gross proceeds of approximately £130 million (approximately €150 million). The proceeds are intended to support the development of the Group's copper growth projects in Spain and provide additional financial flexibility to advance its growth strategy.
Strategic investment in Lara Exploration Ltd.
- On 2 April 2026, the Group acquired 4,500,000 common shares of Lara Exploration Ltd. through a private placement for a total consideration of C$13.5 million. Following completion of the transaction, the Group held approximately 7.3% of Lara's issued and outstanding share capital. The investment has been designated as a financial asset at fair value through other comprehensive income in accordance with IFRS 9 Financial Instruments. Further details are provided in Note 14.
Share-based payment awards
- On 28 April 2026, the Company announced the grant of conditional share awards to executive directors, PDMRs and certain employees under its long-term incentive arrangements. The awards are subject to the applicable vesting and performance conditions and are accounted for in accordance with IFRS 2 Share-based Payment.
28. Events after the Reporting Period
- On 12 October 2026, the Company announced that Proyecto Touro, through its local entity Cobre San Rafael, had been designated as a Strategic Project by the European Commission under the European Union’s Critical Raw Materials Act (“CRMA”). The European Commission announced the designation on 9 October 2026.
The EU designation recognises the strategic importance of Proyecto Touro in contributing to a secure and sustainable European supply of copper, which has been included on the EU’s list of strategic raw materials as a result of being essential to electrification, energy infrastructure and industrial development.
- On 21 October 2026, the Company announced the issue of 181,292 ordinary shares of €0.09 each (the “New Shares”), representing approximately 0.12% of the Company’s issued share capital, to certain eligible employees in relation to the Company’s Long-Term Incentive Plan 2020. The announcement stated that admission of the New Shares to trading would increase the total number of ordinary shares in issue to 153,940,335.
- On 11 November 2026, the Group completed the acquisition of 100% of the shares of Tharsis Mining, S.L., a private Spanish company which, through its subsidiaries, owns the Tharsis and La Zarza projects in the Iberian Pyrite Belt, southwest Spain.
Total cash consideration amounted to €125 million, comprising €75 million paid on completion from the Group’s existing cash resources and deferred consideration of €50 million payable within 12 months of completion. The deferred payment is secured by a bank guarantee and bears interest at 12-month EURIBOR plus 1.5%. The acquired group retains certain legacy and contingent liabilities estimated at approximately €7 million. The acquisition expands the Group’s portfolio of development and exploration projects in its core operating region.
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.